What If Your Bank Valuation Is Below the Price in Dubai?
Work out the extra cash you may need when a Dubai bank values a home below the price you agreed, and see which figures you can ask the valuer to review.
If your bank values a Dubai property below the agreed price, the mortgage can shrink and you may need more cash to complete. As of 18 November 2026, the Central Bank measures loan-to-value against the appraised value. Ask for the bank's revised loan amount, then subtract it and any payments already credited to the price from what you agreed to pay.
Checked 18 November 2026 · the iOffPlanDubai team.
How much extra cash does a low bank valuation cost you?
At the same loan-to-value percentage, the extra cash is the amount the loan shrinks by. A valuation AED 200,000 below the price cuts an 80% loan by AED 160,000 if valuation sets the loan size. Use the lender's revised written offer for your own calculation.
Hypothetical example. You agreed to pay AED 2,500,000 and planned to borrow 80%. The bank accepts a valuation of AED 2,300,000. Assume it lends 80% of that value, your affordability supports the amount, and AED 250,000 you've already paid is credited to the price.
| Amount in AED | At the agreed price | At the lower valuation |
|---|---|---|
| Value used in the example | 2,500,000 | 2,300,000 |
| Loan at 80% | 2,000,000 | 1,840,000 |
| Your full contribution to the price | 500,000 | 660,000 |
| Cash still due after the credited 250,000 | 250,000 | 410,000 |
Keep unpaid costs in a line of their own. On a mortgage value of AED 1,840,000, Dubai Land Department (DLD) lists a 0.25% registration charge, which comes to AED 4,600 before the other charges that apply to your route. Ask the bank or registration trustee for the full amount and when it falls due. Check how the contract treats any deposit cheque still being held before counting it as money already paid.
If the bank was already going to lend only AED 1,700,000 because of your income, the new valuation might leave that offer unchanged. If it cuts the offer for another reason as well, subtract the amount it now expects to release.
Sources · CBUAE Mortgage Loan Regulations, Articles 1–3 · DLD mortgage registration fees · Checked 18 November 2026.
Why can the bank's figure be lower than the price?
The Central Bank of the UAE (CBUAE) requires a qualified, independent third party to value the property on site before the lender makes an irrevocable commitment. Your agreed price records what you're willing to pay. The valuation gives the lender a figure for the home securing the loan.
If you're paying extra for a renovated kitchen or a larger terrace, look at the sales behind the valuation. Ask whether the report describes those features and whether the recent sales the valuer used had them. In a new building with few finished-unit sales, ask which other buildings the valuer used and why. An asking price, a developer's launch price and a registered sale are three different things, so note which one each figure is.
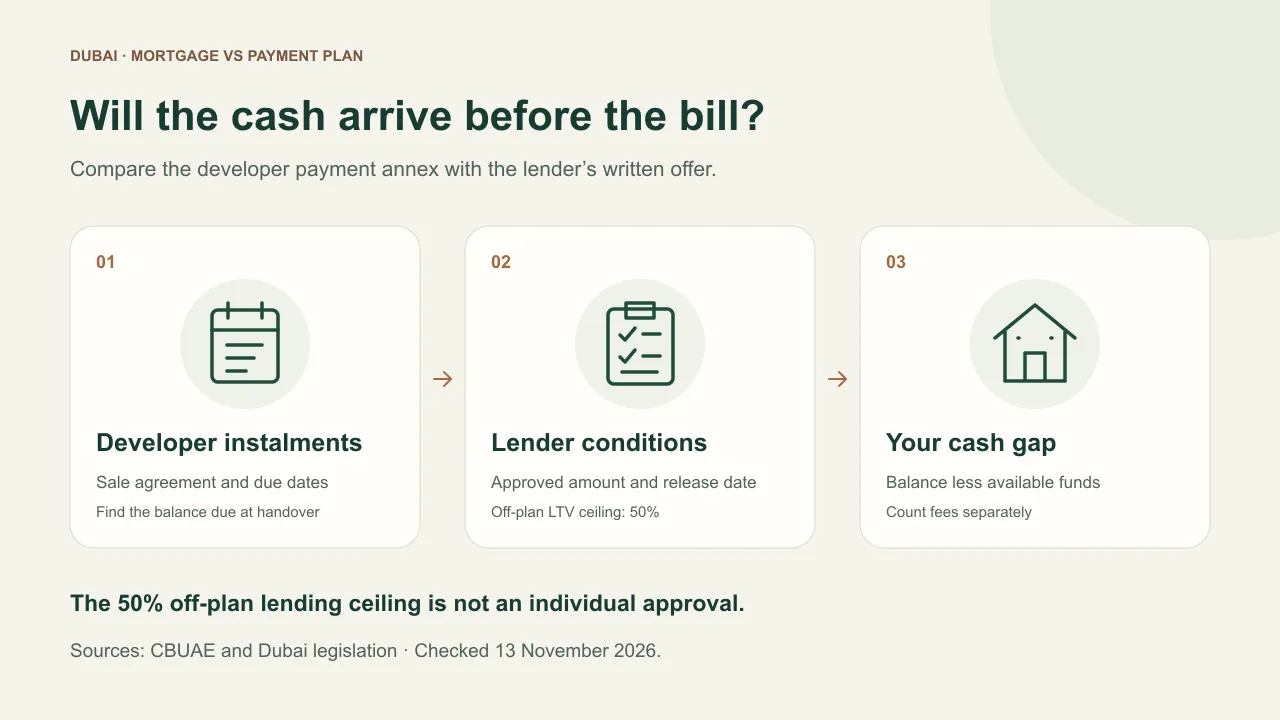
Check the bank's lending category too. Article 3 sets a ceiling of 80% for an expatriate's first owner-occupied home valued below AED 5 million. It lists 60% for an expatriate's second or subsequent home or investment property and 50% for mortgages on purchases classed as off-plan. Your lender can offer less. If you're approaching completion, ask which category the bank will apply on the release date and read the handover instalment mortgage guide.
Sources · CBUAE Mortgage Loan Regulations, Articles 2–3 · DLD Dubai Real Estate Valuation Guide · Checked 18 November 2026.
How do you ask the bank to review a low valuation?
- Get the figure and its date. Ask for a copy or a summary of the valuation, the property value the bank accepted and the revised offer. Ask which limit cut the loan. If the lender also reduced what it will lend against your income, a higher valuation alone may leave the amount unchanged.
- Check that the report describes your unit. Put it beside the title deed or initial-sale certificate and the signed floor plan. Match the tower, unit, measured area and any parking or terrace included in the sale. If two figures differ, check the area basis before calling it an error.
- Pull comparable sales. Use DLD Real Estate Data for registered transactions. Start with the same building or phase, similar size and room count, and the same registration type. Save the transaction date, amount and area in square metres. For each match, note the differences you can verify, such as the layout or parking. Ask the valuer to explain any difference the public record can't show.
- Ask what the bank will accept. Send the lender the disputed detail and the document that supports the correction. For a comparable sale, give the transaction reference and explain why it's a closer match. Ask who reviews it, whether a fresh inspection costs extra and when you'll get a decision. We couldn't confirm a standard review fee or deadline.
Before you pay for a separate DLD valuation certificate, ask if the bank will consider it. DLD issues that certificate through its own service. The lender decides what evidence it takes from you and which valuer it uses for the loan.
Sources · DLD Real Estate Data · DLD Property Valuation · Checked 18 November 2026.
What can you do if the valuation stays low?
Cover the difference. Use the revised offer to work out what you would pay on completion. Add any applicable bank and registration charges and check what cash you'd still have for the home after the transfer. Under the Central Bank's mortgage rules, the down payment should come from your own resources. The rule excludes borrowing such as a personal loan or credit card for that contribution.
Ask for a new price. Show the seller the bank's figure and the actual loss of finance. In the example above, a signed price of AED 2,400,000 with the same AED 1,840,000 loan and AED 250,000 already credited would leave AED 310,000 to pay toward the price. Have the bank confirm the loan against the amended agreement before working to that figure.
Check another lender. Send the same property and borrower details and ask whether it will consider the unit and when it could complete. Compare the new valuation cost, processing charge, rate and release conditions with the bank you already have. A fresh file can use up time and money. Emirates NBD's February 2026 Home Loan Key Facts Statement, for example, lists AED 3,150 including VAT for a completed-property valuation. Get your own quote before booking another one.
Read the contract before deciding whether to withdraw. For a resale, use the Form F and signing checks and open the signed clauses on finance, valuation, notice and deposit. For a developer purchase, open the sale and purchase agreement (SPA) and payment annex. Ask a Dubai property lawyer whether the wording covers a low valuation, what evidence the other party needs and what happens to money already paid. If you need more time, ask the seller or developer to confirm a revised deadline in writing.
Sources · CBUAE Mortgage Loan Regulations, Article 2 · Emirates NBD Home Loan Key Facts Statement · Checked 18 November 2026.
What should you settle before you sign?
Get an approval in principle to put a number on your budget, then have the bank assess the unit. HSBC explains that an approval in principle gives you an indication of what it could lend after an initial assessment of your finances. Leave room in your budget for a lower appraisal before you commit to a price. CBUAE's disclosure standards cover the written credit offer and the Key Facts Statement. Use the offer to check the amount approved and the fee schedule to see which costs you pay before completion.
Put three dates in the same calendar: the latest day to notify the seller under the finance clause, the last date your bank can release under the offer, and the transfer or instalment deadline. If approval depends on a valuation threshold or on a minimum loan, ask your lawyer to check that the contract spells out which figure triggers the clause and what written proof counts. If you're still choosing how to finance an off-plan purchase, compare the mortgage and developer payment plan against the cash you can have ready on each date.
Sources · CBUAE Consumer Protection Standards, sections 2.1.1 and 2.1.3 · HSBC UAE approval in principle guide · Checked 18 November 2026.
If the new loan will replace an existing one, include the early mortgage settlement fee and release costs when you compare the two offers.
Use the bank's revised release amount in the Dubai handover costs timeline. If you already used that amount, the lower valuation is already counted.
What else can change the amount you pay?
Will a low valuation automatically change the purchase price?
Work from the price in your signed contract unless the parties agree a change or a clause applies. Ask the lender to use any written amendment when it updates your offer. If the seller disputes what the clause says, have a Dubai property lawyer read the exact wording and dates.
Can I complain if the bank mishandles my request?
Raise a formal complaint with the bank first and keep the reference and its reply. After 15 calendar days, check Sanadak's eligibility rules if you have no written response or are unhappy with it. Sanadak can reject matters that materially concern the bank's risk management or internal pricing, among other exclusions. Keep working to your contract deadline while the bank responds. Sanadak complaint eligibility · Checked 18 November 2026.
What if the bank values the property above the sale price?
Ask the bank what value it will use to size its loan and what it will release for the purchase. Keep the agreed price and accepted value on separate lines. A higher appraisal on its own tells you very little about how much cash the bank will actually advance.
If you've just received the valuation, ask the bank for the revised offer and its release conditions today. Put the resulting cash figure beside the next date on your contract.
Sources
- Central Bank of the UAE · Regulations Regarding Mortgage Loans — rulebook.centralbank.ae · checked
Consolidated Circular 31/2013. Articles 1–3 cover appraised value, independent valuation, borrower funds, affordability and LTV ceilings expressed as percentages of property value.
- Central Bank of the UAE · Consumer Protection Standards — centralbank.ae · checked
Sections 2.1.1.19, 2.1.1.37 and 2.1.3.9 cover the Key Facts Statement, applicable fees and the written offer with the approved amount.
- Dubai Land Department · Dubai Real Estate Valuation Guide — dubailand.gov.ae · checked
Official guidance on valuation methods, property characteristics and market evidence.
- Dubai Land Department · Real Estate Data — dubailand.gov.ae · checked
Published transaction fields include date, amount, registration type, property size in square metres, parking and project.
- Dubai Land Department · Property Valuation — dubailand.gov.ae · checked
DLD's own valuation certificate service, including residential units and villas.
- Dubai Land Department · Mortgage registration application — dubailand.gov.ae · checked
The registration percentage is 0.25% of the mortgage value. Other charges are listed in AED by route.
- Emirates NBD · Home Loan Key Facts Statement — cdn.emiratesnbd.com · checked
February 2026 document illustrating a lender's completed-property valuation charge of AED 3,150 including VAT.
- HSBC UAE · Guide to mortgage approval in principle — hsbc.ae · checked
An initial view of borrowing capacity before final lending approval.
- Sanadak · Complaint Eligibility — sanadak.gov.ae · checked
Bank complaint first, 15 calendar days and other eligibility criteria including possible exclusions for risk management and pricing.
Next stepDubai Properties Service Charges: DLD Index & Calculator →
More in Ownership costs
Start here: Dubai Properties Service Charges: DLD Index & Calculator
- Laundry services in UAE apartments: what a week costs
- Dubai Off-Plan Handover Costs: What You Pay and When
- Renting vs buying a house in Dubai at two move-out dates
- Dubai Building Completion Certificate Check (5 Steps)
- Should You Buy Dubai Property Through a Company?
- What Is the Early Mortgage Settlement Fee in Dubai?