Renting vs buying a house in Dubai at two move-out dates
Renting vs buying a house in Dubai depends on when you move. Compare two exit dates, Dubai transfer fees and the cash you’ll have left after a sale.
Renting vs buying a house in Dubai comes down to your move-out date. As of 19 November 2026, a short stay favours renting when the cost of buying and selling exceeds the rent you’d save. A longer stay can reverse the result, even if the house never rises in value.
Price the house you’d rent and the one you’d buy for two dates: the end of your work assignment and the year you’d move if your family stayed.
Renting vs buying a house in Dubai: when do the numbers change?
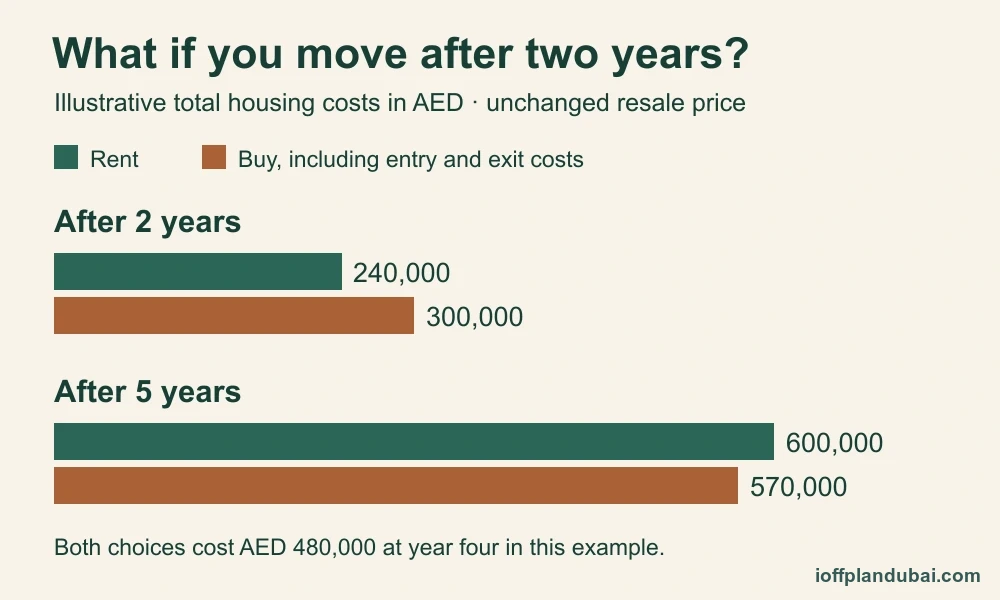
Suppose the annual cost of renting a house is AED 120,000 and the annual cost of owning the equivalent house is AED 90,000. If buying and selling together cost an extra AED 120,000, you need four years of AED 30,000 savings to recover that money. Moving after two years produces a different answer from moving after five.
| Move-out date | Total cost of renting | Ownership cost including entry and exit | Lower cost |
|---|---|---|---|
| End of year two | AED 240,000 | AED 300,000 | Rent by AED 60,000 |
| End of year four | AED 480,000 | AED 480,000 | Equal |
| End of year five | AED 600,000 | AED 570,000 | Buy by AED 30,000 |
These are hypothetical household budgets. The rental figure includes the tenant’s annual costs. The ownership figure allows for interest, upkeep, charges, insurance and the earnings forgone on cash tied up in the home. The example holds those totals flat, assumes an unchanged resale price and treats the AED 120,000 as the buyer’s extra one-off costs after allowing for the renter’s. Replace each with your own terms.
Now change the sale price. If the house sells for AED 60,000 less than you paid, the five-year ownership cost rises from AED 570,000 to AED 630,000, keeping fees fixed for illustration. Renting now comes out AED 30,000 ahead. That difference tells you how much your decision depends on the sale price.
How much cash do you need before you get the keys?
For a purchase, get a written breakdown of what leaves your account on transfer day and what you’ve already paid towards the price. A reservation deposit credited against your down payment belongs on the calendar once. Keep the bank’s valuation and final loan amount alongside the price. Any gap between the money the bank releases and the amount due to the seller needs funding by the transfer date.
Dubai Land Department lists a buyer share of 2% and a seller share of 2% of the sale value for its completed-property sale route. On an illustrative AED 2 million purchase, each published share is AED 40,000. Check who agrees to cover each share in your contract. DLD also lists a service partner fee of AED 4,000 plus VAT for a sale of AED 500,000 or more. Ask the trustee for an itemised total, including the applicable document charges. DLD property sale registration
A rental needs its own calendar. Write down the first rent payment, refundable security deposit, registration, moving costs and any agreed fee. For eligible tenants and self-managing individual owners using Dubai Now, DLD gives a total of AED 177.75 for tenancy registration. Other channels need a separate quote. Check when the next rent cheque falls due against the dates your salary or housing allowance arrives. DLD tenancy registration via Dubai Now
What does a mortgage payment really cost?
Ask your lender for the repayment schedule and circle the balance on each of your two move-out dates. The interest is a cost of borrowing. The principal you repay reduces what you owe when you sell. Put the full instalment in your monthly household budget, but count only the interest when you use the cost comparison above.
For example, suppose you borrow AED 1.5 million and owe AED 1.35 million on the date you sell. You’ve repaid AED 150,000 of principal. If the house sells for AED 2 million, the proceeds after clearing that loan are AED 650,000 before selling costs. Subtract the seller’s charges from those proceeds. Adding another AED 150,000 for the principal would count the same money twice.
Ask what happens after any fixed-rate period. Have the lender show the payment at the follow-on rate and at a higher rate you want to test. Record the month that change begins. A family that can manage the average cost over five years can still struggle when the mortgage resets in the same month as school fees.
Paying cash removes the mortgage payment but commits more of your savings. Use what that money would reasonably earn in the account or investment you’d otherwise keep, after its costs. If you’d keep your deposit in cash for a move next year, a hoped-for stock market return is a poor comparison.
Which yearly bills belong on each side?
Ask for the villa’s last service charge statement and look up the same project, use and budget year in the DLD Service Charge Index. Check the billed area on the statement before multiplying a rate by the house size. For help matching the approved budget to a particular unit, use the owner’s guide to Dubai service charges.
Walk through the house with the lease or sale particulars in hand. Who services the air conditioning? Who pays if a pump needs replacing? A tenant may have an agreed maintenance contribution. An owner needs to budget for work inside the property as well as anything the community charges. Ask for recent invoices if the owner says the pool or garden is inexpensive to run.
Compare the bills on like terms. If the rental includes garden care, put the cost of a gardener on the ownership side. If the homes use different cooling arrangements, ask for bills covering hot and cooler months. Check the Dubai Municipality housing fee separately from electricity and water usage. Don’t carry a tax rate from another country into the Dubai budget.
What do you gain or give up by renting?
Renting lets you try the school run and find out how the neighbourhood works on a weekday before committing your down payment. That matters when your office may move or you’ve only seen the house on holiday. Read the early-exit clause while you still have a choice of houses. How much rent would you owe if your employer moved you in March?
On renewal, keep two figures side by side. One is what it costs to stay under your current agreement. The other is the full cost of a new lease elsewhere, including the move and any overlap. The Dubai rental price guide explains which question the official index answers and when you need a written offer for a comparable home.
Buying gives you control over how long you keep the house. If adapting a bedroom or changing the garden is part of the appeal, check the community’s approval requirements and get a written price for the work. Put that spend on the ownership side in the year you’ll pay it. Leave it out of the expected sale proceeds unless you have evidence a buyer would pay more for it.
What if the house you want to buy is off-plan?
Use the date you can live in the house as the dividing line. Before then, enter every instalment against its due date and keep your current rent in the same calendar. A construction milestone might trigger a payment while you’re still paying for another home. Read the milestone wording in the agreement alongside the mortgage and developer payment plan comparison.
Suppose your lease is AED 120,000 a year. Six extra months in rented accommodation would add AED 60,000 at that annual rate, assuming you can agree a six-month extension on the same terms. Ask for the actual extension price. A landlord who will only offer a full year changes both your cash requirement and the date when moving makes financial sense.
Before paying to reserve, match the project, house number, plot and beneficiary to the developer’s documents and the official project record. Ask what happens to the reservation payment if finance falls short. For a ready house, ask the seller to confirm the vacant possession date in writing. Either purchase can leave you paying for two places if the keys arrive after your lease renewal.
FAQ
Is there a minimum number of years you should stay before buying?
Divide your extra purchase and sale costs by the annual saving from owning. This gives a rough break-even period if the annual amounts stay flat and you sell at the purchase price. If owning costs more each year before resale, extending your stay won’t recover the entry costs on those assumptions. Model changes in rent, borrowing costs and sale value separately.
What if you might transfer overseas and keep the villa?
Make a third comparison for becoming a landlord. Get a realistic annual rent for an equivalent house and allow time between tenants, management costs, repairs and continued mortgage payments. Test whether your family can cover the Dubai property and the new home during an empty period. A tenancy that starts months after your move won’t help pay the first bills abroad.
How much will you actually take away if you sell early?
Ask the bank for a payoff estimate for the sale date. Deduct the outstanding debt and all quoted sale and release costs from the amount the buyer will pay. The early mortgage settlement guide explains which items to check on the lender’s quote. Use the cash left after settlement when deciding whether you could fund your next home.
Sources
- Dubai Land Department — Property Sale Registration — dubailand.gov.ae · checked
Completed-property sale registration. Each party’s published share is 2% of sale value. Service partner fees are in AED per transaction, plus VAT. The worked household example uses separate illustrative assumptions.
- Dubai Land Department — Register / Renew / Terminate Tenancy Contract via Dubai Now — dubailand.gov.ae · checked
AED 177.75 total on this channel, including VAT on the service fee. Eligibility and steps apply to self-managing individual owners and users with valid Emirates ID.
- Dubai Land Department — Service Charge Index — dubailand.gov.ae · checked
Official lookup by project, usage and budget year. No rate or invoice for an individual house is assumed.
- Dubai Land Department — Rental Index — dubailand.gov.ae · checked
Official rental index for checking an existing contract. A new lease needs its own written rent in AED per year.
Next stepDubai Properties Service Charges: DLD Index & Calculator →
More in Ownership costs
Start here: Dubai Properties Service Charges: DLD Index & Calculator
- Cheapest property in Dubai: areas and buying costs (2026)
- Laundry services in UAE apartments: what a week costs
- Dubai Off-Plan Handover Costs: What You Pay and When
- What If Your Bank Valuation Is Below the Price in Dubai?
- Dubai Building Completion Certificate Check (5 Steps)
- Should You Buy Dubai Property Through a Company?