What Is the Early Mortgage Settlement Fee in Dubai?
Check the UAE cap, the payoff amount in your bank’s quote and the steps to release the mortgage from your Dubai property record.
As of 18 November 2026, the UAE Central Bank caps early mortgage settlement fees on retail home loans at 1% of the outstanding balance or AED 10,000, whichever is lower. Ask your bank for a payoff quote dated for your planned payment, then arrange the release with Dubai Land Department (DLD).
Checked 18 November 2026 · the iOffPlanDubai team. Central Bank of the UAE, Consumer Protection Standards, annexure row 35 · DLD mortgage release application.
How do you check the early mortgage settlement fee Dubai banks quote?
Multiply your outstanding home loan balance by 1% and compare it with AED 10,000. The lower figure is the ceiling in the Central Bank of the UAE (CBUAE) fee schedule. Use the balance your bank confirms for settlement. Ask it to show the balance, fee and any value added tax (VAT) on separate lines.
| Example balance (AED) | Balance × 1% (AED) | Fee ceiling (AED) |
|---|---|---|
| 450,000 | 4,500 | 4,500 |
| 1,000,000 | 10,000 | 10,000 |
| 1,400,000 | 14,000 | 10,000 |
Read the fee clause for your product. For example, HSBC UAE's Variable 3-month EIBOR Home Loan schedule lists 1% or AED 10,000, whichever is lower, and shows the VAT-inclusive figures as 1.05% or AED 10,500. It lists different charging periods for a payoff funded by your own cash or a sale and a payoff funded by another lender. Ask which provision your bank is applying and whether the fee is waived under your own terms. If your rate is about to reset, use the EIBOR mortgage guide to check the date against your payoff plan.
Sources · CBUAE Consumer Protection Standards, annexure row 35 and sections 2.1.3.7–8 · HSBC UAE published product schedule · Checked 18 November 2026.
What goes in the bank's payoff quote?
Give the bank your intended payment date, how you'll fund it and the property reference. Request the total payable on that date and ask how long the figure holds. If an instalment falls due before then, get the bank to explain how it will show up in the new balance. Keep the quote and its reference beside any sale or refinance deadline.
| Line to check | What to ask the bank to show |
|---|---|
| Outstanding balance | The amount used for the percentage calculation and the date it applies to |
| Interest or profit | What has accrued and the period the bank used |
| Early settlement fee and VAT | The fee clause, its arithmetic and how much tax was added, if any |
| Letters and certificates | The name, price and recipient of each document requested |
| Total payable and funding | The amount for the planned date, accepted payment method and what to do if the date moves |
The CBUAE requires lenders to disclose how an applicable early settlement fee is calculated and when it is payable. It calls for a worked example in the Key Facts Statement where the fee applies. Section 7.1.5.12 bars future unearned interest from the date of full early settlement and says interest after a partial settlement must be adjusted to the principal that remains.
How long do bank liability letters take?
Two document lines to look for in the annexure are AED 85 for issuing a home-finance liability letter and AED 95 for a home-finance clearance letter, both in the cap column. Ask the bank to name the letter it is charging for. Section 7.1.1.9 gives the lender seven complete business days from your request to issue the applicable liability or no-liability letter. Ask separately when the bank can send the release instructions for the property.
Sources · CBUAE Consumer Protection Standards, sections 2.1.3.7–8, 7.1.1.9 and 7.1.5.12, annexure rows 36 and 42 · Emirates NBD early settlement instructions · Checked 18 November 2026.
If the alternative is a developer plan, put the payoff quote beside the developer’s outstanding balance on the same date. The mortgage and payment plan comparison shows how to compare both exits.
Should you ask for full or partial settlement?
If you want to clear the loan and remove the mortgage from the property record, request full settlement. If you want to pay down part of the loan, tell the bank the amount and ask for the payment schedule after the reduction. Ask whether it will change your monthly payment, the remaining term or both. Put the revised schedule beside the existing one and include any fee in the comparison.
The standards give partial settlement its own fee line. Row 41 sets the same ceiling wording, 1% of outstanding balance or AED 10,000, whichever is lower. Ask how your lender actually charges for the amount you plan to pay. For the HSBC product above, the bank publishes a fee-free annual overpayment allowance of up to 25% of outstanding balance, with conditions on the minimum payment and when it is made. The lender's schedule explains how it charges on any excess for that product.
Sources · CBUAE Consumer Protection Standards, annexure row 41 and section 7.1.5.12 · HSBC UAE overpayment rules · Checked 18 November 2026.
How do you remove the mortgage from the Dubai property record?
If you're keeping the property and clearing an ordinary mortgage, ask your bank whether it will submit through DLD's online mortgage system. DLD lists the owner's Emirates ID for identification. A bank employee uploads the documents, DLD checks the file, the fees are deducted from the bank's account and the outputs arrive by email. Ask the bank for the submission reference and how it collects the DLD charges from you.
If the release is part of a sale or the mortgage is provisional, ask a Real Estate Registration Trustee what they need before you book. DLD directs these cases and other special categories, including usufruct and portfolio mortgage releases, to the registrar route. Its standalone trustee checklist lists a bank letter for mortgage removal and the owner's Emirates ID for identification. If you hold a passport only or someone will attend on your behalf, ask the trustee what it accepts for that procedure. What a Dubai registration trustee handles.
When DLD finishes, save the emailed release document if issued and check the property identifier and ownership details on the output. Depending on the record, DLD can issue a title deed or a provisional sale registration certificate (Oqood). If you paid off the loan and only have a bank confirmation, ask for the DLD application reference and the expected property document. DLD mortgage release application · Checked 18 November 2026.
What does DLD charge and how long does it take?
The standalone release service lists these charges. Ask the bank or trustee which lines apply to your file before you set aside money.
| DLD standalone release line | Published fee |
|---|---|
| Mortgage removal | AED 1,000 |
| Title certificate or deed, where applicable under the service card | AED 250 |
| Knowledge and innovation fees | AED 10 each per drawing |
| Service partner fee | AED 300 plus VAT on that fee |
DLD lists 10–15 minutes as the expected service time. Ask the bank when the payoff clears, who requests the release and when they expect to submit it. Budget time for those steps before counting on the DLD service window. We couldn't confirm a single settlement-to-release time across lenders. For a file already submitted, ask which side has it and give the bank or trustee the reference from your receipt or email. DLD fees and timing · Checked 18 November 2026.
What changes if you're selling?
For a sale with an existing mortgage, use DLD's mortgaged-sale route through a trustee. For individuals, DLD lists the bank liability letter, the parties' identification and manager's cheques for the debt, any balance to the seller and the DLD fee. Ask the trustee to confirm each payee and amount before the cheques are prepared. The trustee records the transaction, the debt cheque goes through the seller to the bank and the parties submit the bank's mortgage release letter to complete registration. Use the Dubai title transfer guide to plan the registration alongside the payoff.
If you may move again soon, put the bank’s settlement figure into your comparison of renting and buying at two move-out dates.
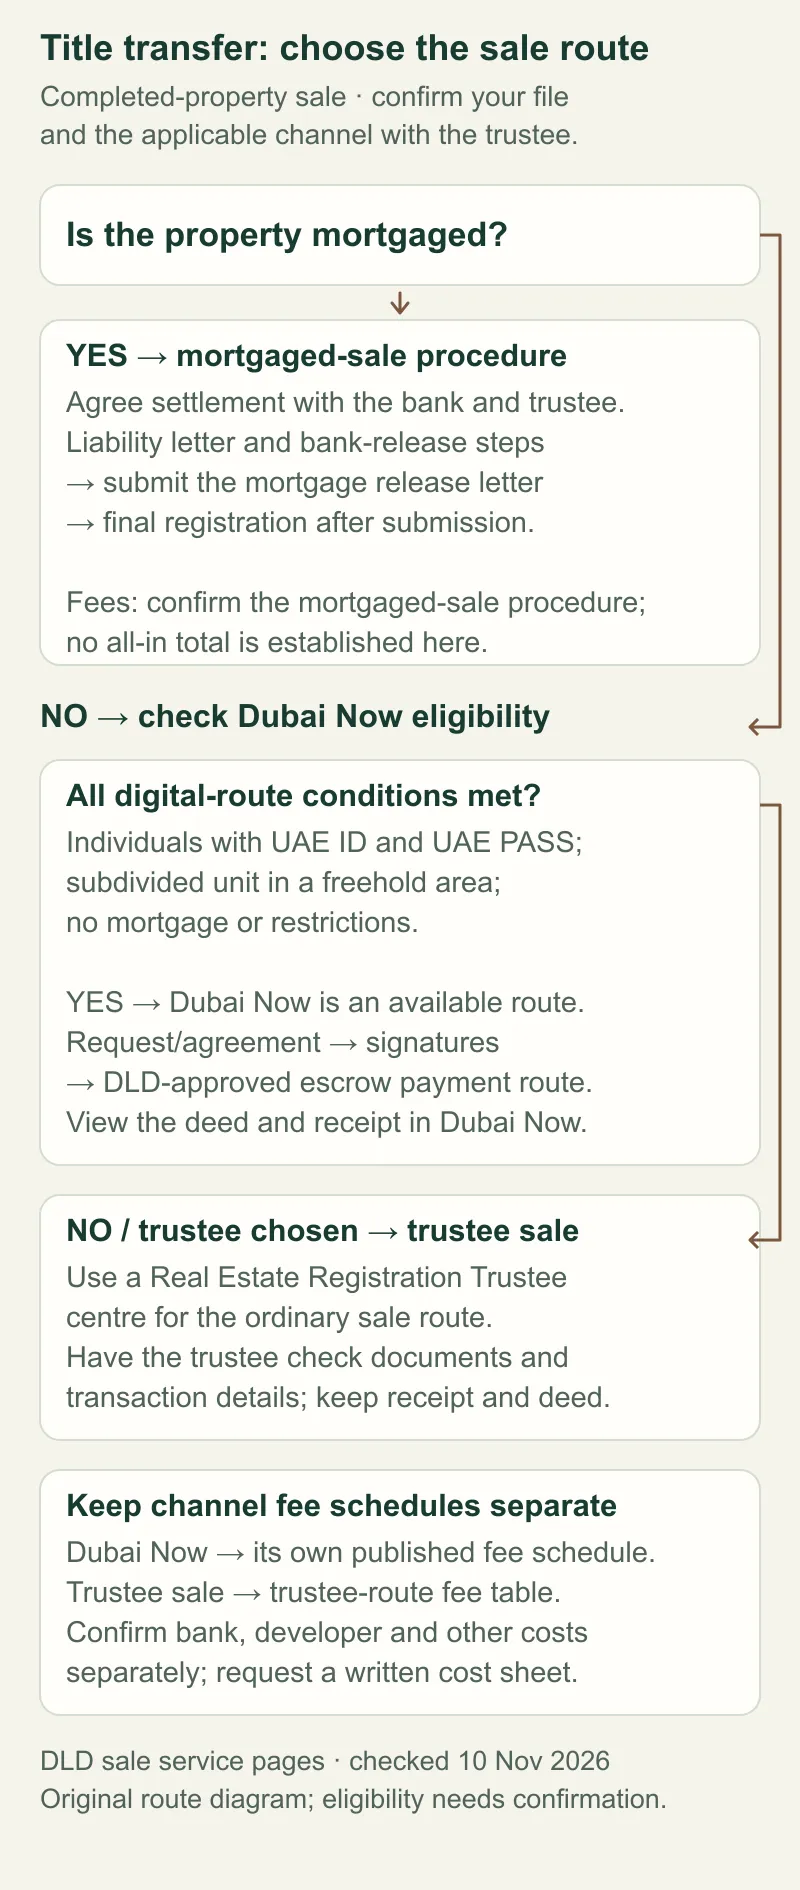
Before the bank issues the payment, use the manager’s cheque payee checklist to reconcile the liability letter, seller’s balance and DLD fee.
A hypothetical sale illustrates the handoff. If the bank's dated figure is AED 450,000 and the buyer intends to fund it from the price, ask the trustee to put that amount beside the payee and the deadline for issuing the cheque. Then ask who will collect the release letter and bring it back to the trustee. If the bank's figure expires before the appointment, get the updated figure before anyone orders a replacement cheque. DLD's mortgaged-sale card lists AED 1,290 for the mortgage release and AED 315 for the registrar to release it, alongside other sale charges. Ask the trustee for a breakdown for your transaction.
What changes if you're refinancing?
Put the old bank's quote beside the new lender's written offer. Ask the banks which one funds the payoff and which DLD procedure they will use. DLD's mortgage transfer service lists a no-objection letter from the old bank, a letter from the new bank and certified mortgage contracts for the individual trustee route. It lists a charge of 0.25% of the mortgage value, plus other lines. Ask for the total for your file.
Use the bank valuation and cash gap guide if the new lender's offer depends on an updated valuation. Compare the old loan's remaining payments with the new schedule and the charges for switching. Check the remaining term in months on both offers if the new monthly payment looks lower. DLD mortgaged-sale procedure · Emirates NBD early settlement guidance · Checked 18 November 2026.
What if the quote or release is wrong?
Ask the bank for an itemised correction and keep the reply with the dated quotation. If a fee looks above the published ceiling, ask which type of charge it is, which balance was used and whether the amount includes VAT. For an unresolved bank complaint, keep the formal complaint reference. Sanadak asks whether 15 calendar days have passed since you complained to the bank and whether you received no written reply or are dissatisfied with it. Check its remaining eligibility questions before filing. For a DLD processing issue, give the release reference to the submitting bank or trustee. Sanadak eligibility · DLD release procedure · Checked 18 November 2026.
What should you check after paying off the mortgage?
What happens to postdated cheques held by the bank?
If you provided postdated cheques for the financing, the CBUAE standards require the bank to return the remaining ones within seven complete business days of early payoff. Ask how to collect them and get confirmation if the bank holds any other security. CBUAE Consumer Protection Standards, section 7.1.1.8.
What if an instalment is still scheduled after you pay?
Ask the bank to confirm the payoff is posted and tell you when to stop the regular payment instruction. If a deduction is already in process, ask the bank to show how it will account for it. Keep that reply with the settlement receipt and the property release confirmation.
If you're waiting on the release now, give the submitting bank or trustee your property and payment references and ask for the DLD output for your property.
Sources
- Central Bank of the UAE · Consumer Protection Standards — centralbank.ae · checked
Annexure rows 35 and 41 cap early and partial settlement fees for home finance at 1% of outstanding balance or AED 10,000, whichever is lower. Sections 2.1.3.7–8, 7.1.1.8–9 and 7.1.5.12 cover disclosures, letters and postdated cheques in complete business days, and interest.
- Dubai Land Department · Mortgage release application — dubailand.gov.ae · checked
Bank and trustee routes, owner identification, mortgage removal letter, fees in AED, 10–15 minute expected service time and electronic outputs.
- Dubai Land Department · Registering the Sale of a Mortgaged Property — dubailand.gov.ae · checked
Liability letter, manager's cheques, bank release letter and sequence at a trustee. Charges in AED and percentages of sale or mortgage value.
- Dubai Land Department · Mortgage transfer application — dubailand.gov.ae · checked
Published documents for the previous and new lenders and a charge of 0.25% of the mortgage value, with additional lines in AED.
- HSBC UAE · Mortgage and Home Loan Rates — hsbc.ae · checked
Variable 3-month EIBOR product example. Fees before and including VAT in AED and percentages, with settlement terms in years and an overpayment allowance per calendar year.
- Emirates NBD · Apply for early loan settlement — emiratesnbd.com · checked
One lender's application guidance, including settlement using own funds or another lender and separate instructions by loan type.
- Sanadak · Complaint Eligibility — sanadak.gov.ae · checked
Formal complaint to the financial institution first and 15 calendar days, subject to the remaining eligibility checks.
Next stepDubai Properties Service Charges: DLD Index & Calculator →
More in Ownership costs
Start here: Dubai Properties Service Charges: DLD Index & Calculator
- What If Your Bank Valuation Is Below the Price in Dubai?
- Dubai Building Completion Certificate Check (5 Steps)
- Should You Buy Dubai Property Through a Company?
- Can a Mortgage Cover Your Final Handover Payment in Dubai?
- Mortgage vs Payment Plan in Dubai (Cash at Handover)
- When Do Dubai Landlords Pay Tax on Rental Income?