Can a Mortgage Cover Your Final Handover Payment in Dubai?
Match your lender’s release date to the developer’s deadline and calculate the cash and registration fees due at handover.
Yes, a bank mortgage can pay the final instalment on a Dubai off-plan purchase if the bank accepts your unit and can release enough money by the developer's deadline. As of 18 November 2026, you'll need the developer's balance and due date in writing, plus the bank's written amount, release conditions and registration route.
Checked 18 November 2026 · the iOffPlanDubai team.
What should you ask the bank about your final handover payment?
Send the bank your sale and purchase agreement (SPA), initial-sale certificate and latest developer statement. Ask whether it can lend while the unit is still on the interim register or only once it's ready for title deed registration. Then ask who will receive the money and on which date the bank can release it. Write down the developer's due date, the bank's latest release date and the expiry date on your offer.
1. What does the developer need and by when?
Ask the developer's handover team for a dated statement for your unit. Match each credited instalment to your receipts. Ask for the amount you must pay now, any amounts due after handover, and the contract clause or payment annex entry behind the due date. Query any difference in writing while there's time to resolve it.
Keep the developer's estimated handover date beside the date on the formal payment notice. For project status, look up the development in Dubai Land Department's (DLD) Project Status Enquiry. The developer's progress update is its own report. Ask which completion certificate has been issued and which document the bank still needs. Use our handover delay guide if the dates move.
For a payment still made under the off-plan purchase, check the project escrow details with the developer and DLD. Ask the bank to confirm the payee, payment method and reference it will use. Match the instructions to your unit before arranging your share.
Sources · DLD Project Status Enquiry · Dubai Legislation Portal, Law No. 8 of 2007 on project escrow · Checked 18 November 2026.
2. Which mortgage route will the bank use?
Dubai's interim-register law allows mortgages on off-plan units entered in the Interim Property Register. Under the Dubai mortgage law, the mortgage goes on the applicable register. For an off-plan mortgage, the Central Bank of the UAE (CBUAE) caps loan-to-value (LTV) at 50% of property value for all buyer categories. Its rules also call for payments linked to construction milestones to be based on milestones physically verified by the lender or a qualifying independent professional.
If the bank will lend only once the property is ready, ask what it needs before treating it as ready and which LTV it will apply. For example, NBK Dubai's mortgage Key Fact Statement allows final payment to the developer on a newly developed property ready for handover, subject to a handover certificate and its express title deed process. Ask your bank for the route on your unit.
Tell the lender whether you'll live there or let it, whether you already have a mortgage, and whether you're applying as a resident or non-resident. The bank also assesses income and debts under the Central Bank's affordability rules. If you're applying from abroad, read the non-resident mortgage guide and ask which signed documents or appointments need you in Dubai.
Sources · Dubai Legislation Portal, Law No. 13 of 2008, Article 6 · Dubai Legislation Portal, Law No. 14 of 2008, Articles 7, 8 and 24 · CBUAE Mortgage Loan Regulations, Articles 2 and 3 · NBK Dubai Mortgage Key Fact Statement · Checked 18 November 2026.
3. How much cash do you need alongside the loan?
Hypothetical example. You bought for AED 2,200,000 and the developer has credited AED 1,210,000. It calls for the remaining AED 990,000. The bank values the unit at AED 1,800,000 and treats it as off-plan. Assume you qualify for the full 50% ceiling and the bank can release all of that toward this payment.
| Handover line | Calculation | Amount |
|---|---|---|
| Due to the developer | AED 2,200,000 − AED 1,210,000 | AED 990,000 |
| Bank funds for the invoice | AED 1,800,000 × 50% | AED 900,000 |
| Your share of the invoice | AED 990,000 − AED 900,000 | AED 90,000 |
| DLD percentage charge alone | AED 900,000 × 0.25% | AED 2,250 |
In this example you'll need AED 92,250 for those last two lines, plus the charges that apply to your transaction. If the bank only approves AED 850,000, your share of the invoice goes up to AED 140,000 and the percentage charge changes to AED 2,125. If the bank can only release after the invoice falls due, you have a timing gap even if the eventual loan is enough. Ask for a revised due date or work out what cash you can have ready by the original one.
The loan-to-value percentage applies to property value. The payment-plan percentage applies to the agreed price. Use the bank valuation cash-gap guide if your valuation comes in below that price. Count only the amount the lender confirms it can send toward this invoice by the due date.
Sources · CBUAE Mortgage Loan Regulations, Articles 1 and 3 · DLD mortgage registration fees · Checked 18 November 2026.
4. What should you get in the bank's written offer?
Get the lender's Key Facts Statement and the written offer for your exact unit. CBUAE's disclosure standards require the approved amount and terms in the written credit offer. Ask for the amount that will reach the developer, itemised fees, the offer's expiry date, the first repayment date and what would need refreshing if handover moves. If there's an introductory rate or profit rate, ask for payments during and after that period.
Send what you have before the payment notice arrives. Ask who supplies each missing item. HSBC UAE, for example, lists identification, a salary certificate, a bank statement and property ownership documents among the items it may request. Ask your lender which accounts and income records it needs if you're self-employed. If the bank needs access for the valuation, ask the developer who can arrange it. There is no standard application-to-release time we could confirm. Ask the bank to give you dates for your file and flag the first one that may slip.
Ask which costs come out of your pocket before release and which the bank will collect later. Get separate figures for valuation, processing and any insurance or takaful premiums. Ask what would be payable again if the offer or valuation expires. Set any service-charge or move-in bill beside the cash schedule with its own payee and due date.
Sources · CBUAE Consumer Protection Standards, sections 2.1.1 and 2.1.3 · HSBC UAE mortgage application documents · Checked 18 November 2026.
If you expect to repay soon after handover, ask the lender to show the fee in its offer and read the UAE mortgage payoff and DLD release steps.
If you’re buying from an existing owner at transfer, use the Dubai property transfer cheque guide to check what the bank will issue and what you’ll need to provide.
5. How do the bank and developer get from Oqood to the title deed?
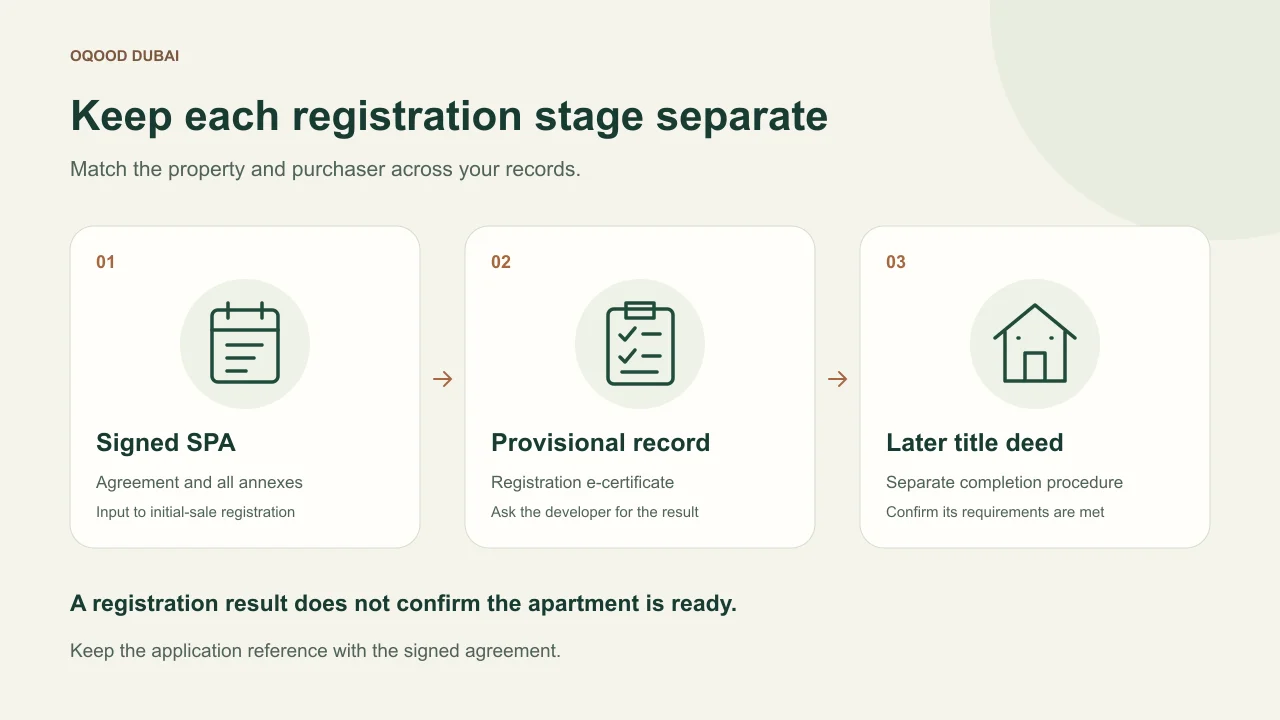
Article 8 of Dubai's interim-register law requires the developer to enter the completed project on the Property Register after obtaining the completion certificate. It also covers registration of units in the names of purchasers who have fulfilled their contract obligations. Article 7 of the implementing bylaw addresses handover and registration once the project is complete, the certificate is issued and the buyer has fulfilled the contractual obligations. Use the Oqood registration guide to match your initial certificate to your SPA before the bank submits anything.
DLD's completion service uses the developer's Oqood portal and issues an electronic title deed and map. If the registration fee has already been collected, the service card lists AED 250 for the deed and AED 250 for an apartment or villa map, plus AED 10 each in knowledge and innovation fees. DLD gives an expected six business days for this service. Ask the developer which charges are already paid and which application its appointment covers.
If the bank says it needs a title deed and the developer says it needs payment first, ask the two teams to agree in writing which steps they can book together. Confirm who submits the title deed and mortgage applications, when your contribution must clear and what releases the bank's part. Ask the developer what it will give you once the invoice is settled, then keep the payment receipt and registration reference with the issued documents.
DLD lists a bank letter, signed bank-certified mortgage contracts and identification for individuals using a trustee office. For provisional sales it also lists an electronic no-objection certificate (e-NOC) from the developer via Dubai REST. Ask the bank which route and document list apply. DLD publishes 0.25% of mortgage value and lists service partner fees of AED 4,000 plus VAT, or AED 5,000 plus VAT for provisional Oqood. The card also lists title deed and drawing-related charges in applicable cases. Ask for the total by line item for your booking.
DLD gives an expected 20–25 minutes for the registration service. Put mortgage registration and the bank's release date on separate lines in your calendar.
Sources · Dubai Legislation Portal, Law No. 13 of 2008, Article 8 · Dubai Legislation Portal, Executive Council Resolution No. 6 of 2010, Article 7 · DLD initial procedures completion service · DLD mortgage registration application · Checked 18 November 2026.
What if the loan won't arrive in time?
Tell the developer which condition is outstanding and give the bank's latest expected release date. Ask for a written revised due date and whether any charge or change to key collection applies. If you're asked to sign a new schedule, have a Dubai property lawyer check what it does to your current obligations and any sums you've already paid. Keep the original date in your cash plan until you have written terms you can rely on.
If a notice has already arrived, use the missed off-plan instalment guide to identify who issued it and which deadline it sets. Keep the notice, developer ledger and bank emails together so you can show DLD or your lawyer the dates and amounts.
What else can affect the handover payment?
Can you mortgage the rest of a post-handover plan?
Ask the developer for a dated settlement figure covering every instalment the bank is meant to clear, and ask the bank whether it can register while any balance remains. Check who coordinates title registration and when the developer will issue confirmation that the agreed balance is paid.
Can you inspect the home before the bank pays?
Ask the developer when it can give you access and check the contract for the inspection and payment steps. Keep the lender's valuation appointment and your own snagging inspection on the calendar. Ask the bank if a reported defect would affect release and ask the developer to record your snag list in writing.
Does paying the full balance first mean you can borrow it back later?
Ask the bank to assess that as a separate application before relying on it. Give the expected title deed date and ask how it would classify the loan after you've paid the developer, what amount could be approved and when it could release funds.
Send both teams the same unit reference and payment date. Ask the bank to confirm what it can release by then, and the developer to confirm how it will credit both the bank's payment and yours.
Sources
- Central Bank of the UAE · Regulations Regarding Mortgage Loans — rulebook.centralbank.ae · checked
Articles 2–4 cover independent valuation, physically verified construction milestones, debt burden and the 50% off-plan LTV ceiling.
- Central Bank of the UAE · Consumer Protection Standards — centralbank.ae · checked
Sections 2.1.1 and 2.1.3 cover the written offer, Key Facts Statement and fee disclosures.
- Supreme Legislation Committee in Dubai · Law No. 13 of 2008 — dlp.dubai.gov.ae · checked
Articles 6 and 8 cover mortgages on the Interim Property Register and registration of completed projects and sold units.
- Supreme Legislation Committee in Dubai · Executive Council Resolution No. 6 of 2010 — dlp.dubai.gov.ae · checked
Article 7 covers handover and registration following completion and fulfilment of obligations under the unit sale agreement.
- Supreme Legislation Committee in Dubai · Law No. 14 of 2008 — dlp.dubai.gov.ae · checked
Articles 7, 8 and 24 cover registration of mortgages and the off-plan route.
- Dubai Land Department · Mortgage registration application — dubailand.gov.ae · checked
Lists documents, provisional e-NOC, fees as a percentage of mortgage value and in AED plus applicable VAT, and an expected service time in minutes.
- Supreme Legislation Committee in Dubai · Law No. 8 of 2007 — dlp.dubai.gov.ae · checked
Covers project escrow accounts for off-plan purchaser and financier payments.
- Dubai Land Department · Project Status Enquiry — backoffice.dubailand.gov.ae · checked
DLD enquiry includes project details and completion percentage.
- HSBC UAE · How to apply for a mortgage — hsbc.ae · checked
Bank-specific examples of identification, income and property documents for a mortgage application.
- Dubai Land Department · Request to complete the initial procedures data — dubailand.gov.ae · checked
Developer Oqood portal route to the electronic title deed and map. Service charges are in AED and expected completion is in business days.
- National Bank of Kuwait Dubai · Key Fact Statement for Mortgage Loans — nbk.com · checked
Bank-specific example of final payment to the developer on a ready-for-handover unit with certificate and express title deed conditions.
Next stepDubai Properties Service Charges: DLD Index & Calculator →
More in Ownership costs
Start here: Dubai Properties Service Charges: DLD Index & Calculator
- Dubai Building Completion Certificate Check (5 Steps)
- Should You Buy Dubai Property Through a Company?
- What Is the Early Mortgage Settlement Fee in Dubai?
- Mortgage vs Payment Plan in Dubai (Cash at Handover)
- When Do Dubai Landlords Pay Tax on Rental Income?
- Dubai property payment plans compared by cash due date