Is VAT Charged on Property in Dubai? A Buyer’s Guide
Is VAT charged on property in Dubai? Check homes, offices and serviced apartments, then see what to ask for when VAT appears on the bill.
Is VAT charged on property in Dubai? As of 18 November 2026, the first supply of a qualifying home within three years of completion is zero-rated, and ordinary residential resales and qualifying later leases are generally exempt. Commercial property and serviced accommodation generally carry 5% VAT when the supplier is required to charge it. Federal Tax Authority real estate guide and UAE VAT law.
Is VAT charged on property in Dubai when you buy or rent?
Start with the use of the unit and the charge on the contract. An office lease generally carries 5% VAT when the supplier must charge it. A later lease of a qualifying home is generally exempt if it meets the lease conditions. An office and a flat in the same tower can therefore have different bills. FTA real estate guide, section 2.3.
| What you're paying for | Published VAT treatment | What to check |
|---|---|---|
| First sale or lease of a qualifying home within three years of completion | 0% | Completion date and any earlier supply |
| Ordinary residential resale or qualifying later residential lease | Exempt | Previous supply and, for a lease, the term or tenant's qualifying ID |
| Office, shop or warehouse | Generally 5% on a taxable sale or lease | VAT status of the supplier and which party accounts for the tax |
| Hotel stay or serviced apartment | Generally 5% on a taxable supply | Unit classification and what the operator supplies |
| Bare land | Exempt | Buildings or civil engineering works already on the plot |
| Mixed-use building | Apply the relevant treatment to each part | Price breakdown between residential and commercial space |
UAE VAT law, Articles 3, 45 and 46, Executive Regulation, Articles 37, 43 and 44 and FTA real estate guide, sections 3, 5–7.
What counts as the first supply of a home?
Ask if the unit has been sold or let before. If a developer lets a qualifying flat after completion and later sells it, the lease comes first for this test. The three-year window runs from completion, which the FTA normally dates from certification by a qualified party. Earlier occupation can set the completion date instead. A first supply after that window generally falls under the residential exemption, subject to the lease conditions where relevant. UAE VAT law, Articles 45 and 46 and FTA real estate guide, sections 3.2–3.3.
Zero-rated and exempt can both leave you with no VAT to pay on the home itself. The difference matters to the supplier. A zero-rated sale is taxable at 0% and can support recovery of eligible input VAT. A landlord making exempt supplies generally can't recover VAT on costs linked to those supplies. So the rent can be exempt while the plumber's invoice still carries VAT. UAE VAT law, Articles 45, 46 and 54–55 and FTA real estate guide, section 3.
A first supply after converting a non-residential building to a residential one has its own zero-rating conditions. If the brochure calls it a new home in a former office building, ask the seller which rule it is applying and for the documents that support it. UAE VAT law, Article 45(11) and Executive Regulation, Article 39.
What VAT should appear on an off-plan payment schedule?
The Federal Tax Authority (FTA) treats a qualifying off-plan home bought direct from the developer as zero-rated. The same guidance covers a partly completed home that meets the residential conditions. For a unit advertised as a residence with a hotel operator, ask the developer to write down the classification and what is included before you rely on a 0% quote. If you're buying a contract assignment, show the FTA or a tax agent the original agreement and assignment terms for a transaction-specific answer. FTA real estate guide, section 3.7 and Executive Regulation, Article 37.
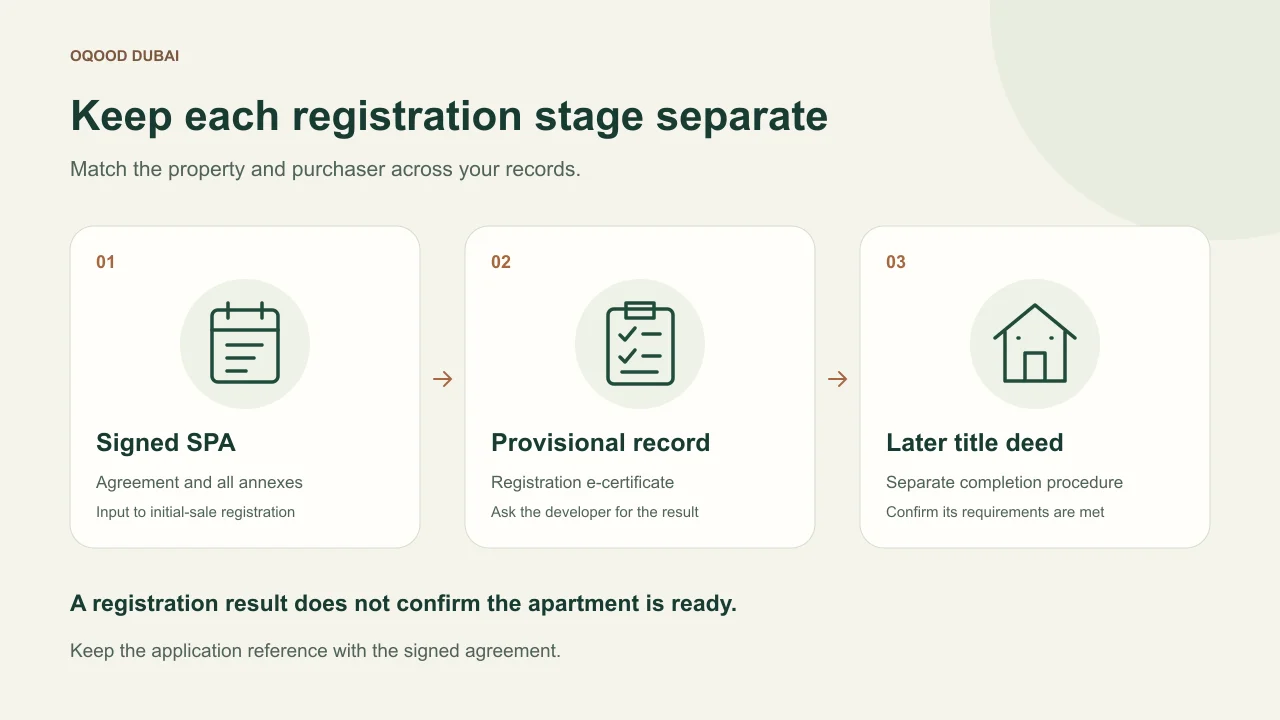
Open the reservation form and the sale and purchase agreement side by side. Match the unit number, use and instalment amounts. Ask for separate lines for the property price, any chargeable services and registration. The off-plan DLD fee and Oqood guide explains how to match the registration line to its receipt. If you're taking over a buyer's contract, the off-plan resale guide explains which transfer documents to ask for.
When does VAT apply to serviced apartments and short lets?
Article 37 excludes “A hotel apartment or serviced apartment or the like” from the residential definition. The FTA guide describes a serviced apartment as one with “services in addition to the supply of accommodation”. If the unit is furnished, ask what else the contract includes and how the supplier classifies the unit. For a branded unit, check the sale and operator agreements side by side. Ask for the treatment of the purchase price and the guest's bill separately. FTA real estate guide, section 3.1 and Executive Regulation, Article 37.
For an otherwise qualifying residential lease, Article 43 gives two routes to the exemption, except where zero-rating applies. The signed term must be more than six months, or the tenant must hold the UAE identity card specified in the regulation. Renewal options don't extend the original term for this test, and an early termination right doesn't shorten it. Start with the building's classification before applying either route. Executive Regulation, Articles 37 and 43.
Example. You're comparing a six-month flat lease with a six-month serviced stay. For the flat, check the tenant's ID and the signed lease term. For the serviced stay, ask the supplier about the accommodation and services it sells and request the full price in writing. Ask for the VAT basis on each written quote. Executive Regulation, Articles 37 and 43.
How does 5% VAT work on an office purchase or lease?
Ask for the price before VAT, the VAT amount and the total in AED. Hypothetical quote. A taxable office lease priced at AED 180,000 before VAT carries AED 9,000 at 5%. The total is AED 189,000, before any other charges. If AED 180,000 already includes VAT, divide it by 1.05 to get about AED 171,429 before VAT. The tax portion is about AED 8,571. UAE VAT law, Articles 3 and 38 and Executive Regulation, Article 27.
For certain commercial resales, the FTA describes a process in which the buyer pays VAT through EmaraTax ahead of transfer and supplies the payment reference to the land department. The guide separates that procedure from commercial leases and sales by the property's developer. Ask the seller and the registration trustee who receives the VAT and which reference they need before the transfer appointment. FTA real estate guide, section 6.4 and FTA commercial-property buyer payment guide.
Watch out for a tenanted office sale. Ask whether the deal includes an operating rental business. The law provides for a transfer of a whole business or independent part to a taxable person who continues it to fall outside the scope of VAT. The leases, what transfers and the buyer's plans matter. Ask for the reasoning in writing before using the VAT figure in your closing budget. UAE VAT law, Article 7 and FTA real estate guide, section 6.4.
Carry the VAT-inclusive figure into your office lease cost comparison so a quote before tax doesn’t appear cheaper than an otherwise identical all-in offer.
What should landlords check about registration and VAT recovery?
The FTA lists a mandatory VAT registration threshold of AED 375,000 in taxable supplies and imports. The test looks at the preceding 12 months or expected supplies and imports in the next 30 days. The voluntary threshold is AED 187,500 and can also count qualifying taxable expenses. Exempt residential rent doesn't count as taxable turnover. A non-resident supplier may need to register without a threshold if nobody else is liable for the VAT on its supplies in the UAE. FTA VAT registration guidance and UAE VAT law, Articles 13, 17 and 19–20.
For a mixed-use purchase, ask the seller for the price attributed to each part. Then keep invoices for costs specific to the office or the homes separate from shared bills such as a common lift repair. A VAT-registered owner can generally recover eligible VAT that relates to taxable supplies. Shared costs may need to be split, and changes in use can affect recovery. Ask the FTA or a registered tax agent how the rules apply to the building and the invoices you hold. FTA real estate guide, section 7 and UAE VAT law, Articles 54–55 and 58.
A qualifying building costing AED 5 million or more before VAT can fall under the Capital Assets Scheme. The regulation sets a 10-year adjustment period for buildings under that scheme. If you're considering changing how the property is used, bring the original VAT invoice, the proposed use and the dates to the FTA or a registered tax agent. Executive Regulation, Articles 57–58.
Why is there VAT on an invoice for a residential property?
Pay attention to the description beside the VAT line. Dubai Land Department (DLD) lists the sale-registration shares separately from the service partner's fee, which it quotes plus VAT. The DLD sale registration page shows where those charges sit. A building manager's charge can also carry VAT. The FTA real estate guide describes the 5% treatment of service charges by a management entity conducting an economic activity and able to register. See the building management and service-charge guide for the records to ask for. FTA real estate guide, section 8.
If the quote says “price plus VAT”, ask which line the tax belongs to. Check the revised quote against the contract before the transfer or the lease starts.
- Property. “What use have you recorded for this unit, and which VAT treatment goes with it?”
- Services. “Which supplier is charging VAT? Can you show the price, VAT amount and total in AED for each charge?”
- Proof. “What VAT registration number should appear on the invoice, and who keeps the payment reference?”
Keep the contract, fee breakdown and tax invoice together. If the classification is unclear, the FTA explains how to raise it through Private Tax Clarifications. UAE VAT law, Articles 38 and 65 and Executive Regulation, Article 59.
What else do buyers and tenants ask about property VAT?
Is an empty plot always exempt?
The test is whether there are completed or partially completed buildings or civil engineering works on it. An unoccupied site can still have works on it, in which case the sale can carry 5% VAT. If the seller calls the plot bare, ask what has already been built and on what date it assessed the plot. Executive Regulation, Article 44 and FTA real estate guide, section 5.
What if the office is in a free zone?
Ask whether the site is a VAT Designated Zone and whether the transaction meets its conditions. The FTA describes certain sales and leases in Designated Zones as outside the scope of VAT. Services on the same site, such as building works or hotel accommodation, can still carry 5%. Executive Regulation, Article 51 and FTA real estate guide, section 11.4.
Can a UAE national reclaim VAT on a new home?
The FTA has a refund route for eligible UAE nationals building new residences. A developer's purchase quote and a claim for VAT on qualifying construction costs are separate questions. Check the FTA's application page for the documents and conditions that fit the build. FTA new-residence refund guidance.
If the rent is exempt from VAT, is the landlord's income outside Corporate Tax?
Check whose name and licence are on the letting agreement. Corporate Tax uses those details to assess an individual's rental activity. The Corporate Tax guide for individual landlords explains the licensing and annual turnover tests. FTA Real Estate Investment guide.
Sources
- Federal Tax Authority — Real Estate VAT Guide (VATGRE1) — tax.gov.ae · checked
Sections 3, 5–8, 11 and 12 cover classification, the three-year window, the 0% and 5% rates, input VAT, service charges and commercial transfer payments.
- Federal Tax Authority — Federal Decree-Law No. 8 of 2017 on Value Added Tax and amendments — tax.gov.ae · checked
Articles 3, 7, 19–20, 38, 45–46 and 54–55 cover rates, transfer of a business, registration, prices, real estate and recovery.
- Federal Tax Authority — VAT Executive Regulation and amendments, September 2026 consolidation — tax.gov.ae · checked
Articles 27, 37–39, 43–44, 51 and 57–59 cover prices, property definitions, the six-month lease condition, bare land, Designated Zones, the capital assets scheme in AED and years, and invoices.
- Federal Tax Authority — VAT registration — tax.gov.ae · checked
AED 375,000 mandatory threshold and AED 187,500 voluntary threshold, with 12-month and 30-day tests and the rule for foreign businesses.
- Federal Tax Authority — Payment for VAT on Commercial Property Sales (Buyer) — tax.gov.ae · checked
EmaraTax payment steps, transaction reference and 5% calculation on the VAT-exclusive price in AED.
- Dubai Land Department — Property Sale Registration — dubailand.gov.ae · checked
Registration shares in percent of sale value and service-partner fees in AED plus VAT.
- Federal Tax Authority — UAE nationals building new residences — tax.gov.ae · checked
Eligibility and application route for qualifying construction VAT refunds.
- Federal Tax Authority — Private Tax Clarifications — tax.gov.ae · checked
Request route for unresolved VAT or Corporate Tax questions.
Next stepDubai Properties Service Charges: DLD Index & Calculator →
More in Ownership costs
Start here: Dubai Properties Service Charges: DLD Index & Calculator
- Mortgage vs Payment Plan in Dubai (Cash at Handover)
- When Do Dubai Landlords Pay Tax on Rental Income?
- Dubai property payment plans compared by cash due date
- District cooling bill Dubai: charges and query steps
- Dubai Municipality Housing Fee: Check Your DEWA Bill
- Central garden in Dubai homes: access and cost checks