When Do Dubai Landlords Pay Tax on Rental Income?
Check how UAE Corporate Tax treats rental income earned by individuals, including holiday-home permits, the turnover test and filing dates.
As of 18 November 2026, rent you earn as an individual from Dubai property is outside UAE Corporate Tax if the letting activity is neither carried on through a licence nor required to have one. If you run a licensed letting business, the AED 1 million calendar-year business turnover test can apply. Cabinet Resolution No. 49 of 2023 and Federal Tax Authority real estate investment guide.
When does corporate tax apply to an individual’s rental income?
Start with the name on the lease and whose licence covers the letting, if it needs one. The Federal Tax Authority (FTA) calls Ejari and similar certificates “administrative records”. The Ministry of Finance distinguishes rent from an online business in the same person's name. Its example puts qualifying rent outside Corporate Tax even when the business passes the threshold. FTA real estate investment guide, section 4.2.2.3 and Ministry of Finance natural persons decision.
| How you earn the rent | Which published rule to read | What to pull out |
|---|---|---|
| You lease a flat yourself without using or needing a licence for the activity | Real Estate Investment exclusion | Lease and Ejari registration |
| Your manager collects ordinary rent for you | The FTA's example of an agent acting for an individual | Management agreement and tenant lease |
| You operate a holiday home under a permit, or need one for that activity | Licensing test and business turnover rules | Permit, guest agreement and receipts |
| You let an office to a company without a licence for your letting | The FTA's commercial-tenant example | Lease, owner name and any permission that covers the letting |
| A company owns or lets the property for its own account | Corporate Tax rules for the company | Title, agreements and the company's accounts |
FTA real estate investment guide, sections 4.2, 4.5 and 5 and UAE Corporate Tax Law, Article 11.
Does an annual lease or a licensed manager change the answer?
Open the signed lease and your management agreement. In the FTA's example, a licensed manager collects rent on behalf of an owner who lets the flat without needing or using a licence. The owner still earns Real Estate Investment income. For the papers that go with an ordinary lease, see the Ejari and tenancy guide. FTA real estate investment guide, sections 4.2.2–4.2.3 and example 5.
If you own an office, check the same question about your activity. In the FTA's example, an individual lets a property to a commercial company for a fixed annual rent. The receipt qualifies as Real Estate Investment because the owner leases without a licence and doesn't need one. In another example, the same treatment applies to an owner who receives AED 50,000 a year plus 7% of the tenant company's revenue and takes no part in the tenant's business. FTA real estate investment guide, examples 2 and 3.
Read the Dubai property VAT guide if you also need to check what appears on an office invoice. Corporate Tax deals with the income of the owner or business. VAT asks about the supply and the person making it. FTA real estate VAT guide and Ministry of Finance Corporate Tax overview.
Whose permit matters for a holiday home?
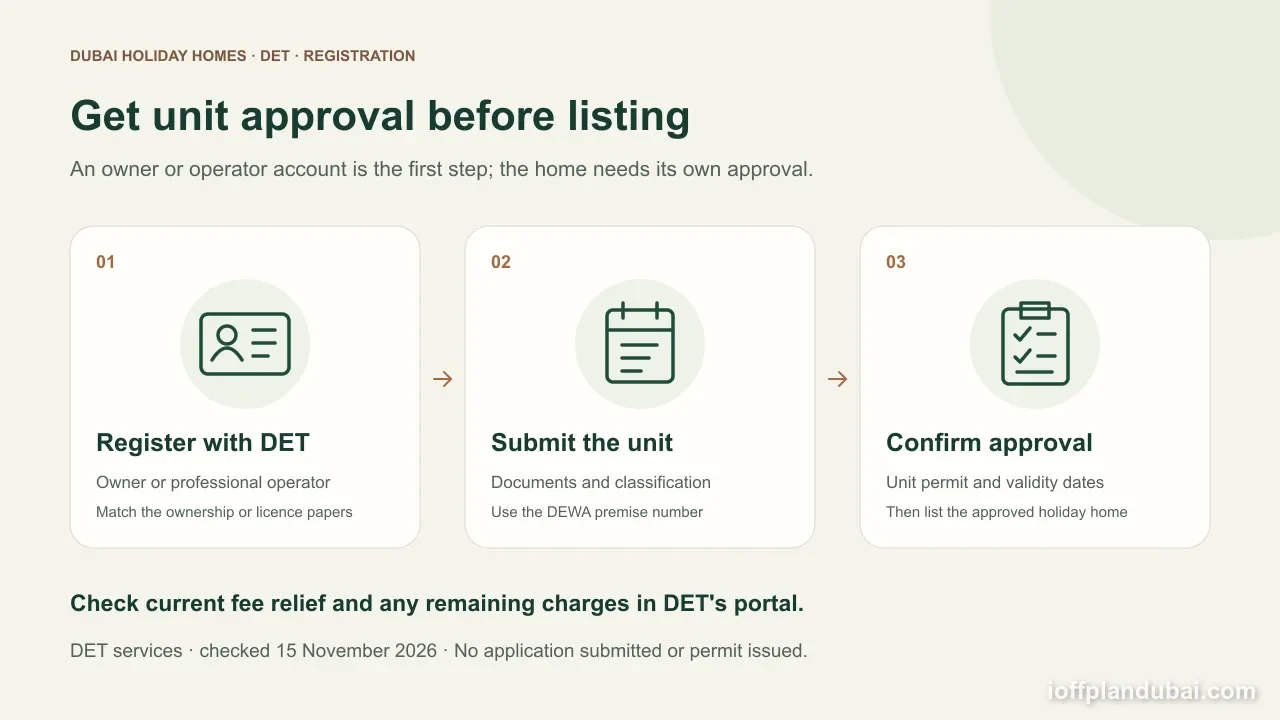
Dubai's Department of Economy and Tourism (DET) issues a Holiday Homes permit for each residential unit that operates as a holiday home. You register the unit in its portal, and the unit shows as approved once the permit fees are paid. The FTA treats a permit allowing an individual to let holiday homes as a relevant licence. Section 4.2.2.4 also covers a licence that is required but hasn't been obtained. The FTA applies the licensing test even if the owner has yet to get the permit. DET Holiday Homes permit service and FTA real estate investment guide, section 4.2.2.
Read the operator agreement alongside the unit permit. Who signs with the guest? Who has the right to let the unit? Does the operator collect the guest's payment for you, or does it pay you under a separate lease? In one FTA example, an individual leases a building to a licensed hotel operator for an annual lump sum. The operator runs the hotel and the individual's lease needs no licence. The guide treats this owner's receipt as Real Estate Investment income. In the next example, the owner runs the hotel under a required licence and the exclusion doesn't apply. FTA real estate investment guide, examples 4a and 4b.
Send DET the proposed agreement and ask whose name must be on the permission. For the account and unit documents, see the Dubai holiday-home permit guide. Put the licensing answer and the proposed agreement to the FTA if the tax treatment remains unclear. DET permit service and FTA Private Tax Clarifications.
What counts towards AED 1 million?
Cabinet Resolution No. 49 uses gross business turnover exceeding AED 1 million in one calendar year. Add up the individual's in-scope business activities together. Leave out wages, qualifying personal investment income and qualifying Real Estate Investment income. Exactly AED 1 million is at the threshold. The trigger is the first amount above it. The Ministry says real estate income “without licensing requirements” is outside Corporate Tax in its example. Cabinet Resolution No. 49 of 2023, Article 2 and Ministry of Finance natural persons decision.
Hypothetical example. One individual earns AED 700,000 in gross receipts from operating licensed holiday homes and AED 350,000 from a separate in-scope business in the same calendar year. Ordinary rent qualifying for the Real Estate Investment exclusion brings in a further AED 240,000. The turnover for the test is AED 700,000 + AED 350,000 = AED 1,050,000. The AED 240,000 stays outside that total. That clears the turnover threshold. You'd need the costs and tax adjustments to work out taxable income. Cabinet Resolution No. 49 of 2023, Article 2 and FTA real estate investment guide, section 4.3.
How do the 0% and 9% rates apply?
For an owner who crosses the threshold, the ordinary rates are 0% on taxable income up to AED 375,000 and 9% on the portion above it. Taxable income starts from accounting income with the adjustments the law requires. Keep the gross receipts used for the turnover test separate from that calculation. Costs of an excluded rental activity stay with that activity. If you pay one common bill for licensed units and ordinary leases that qualify for the exclusion, keep the bill and the basis you used to split it. UAE Corporate Tax Law, Articles 3, 20 and 28, Cabinet Resolution No. 116 of 2022 and FTA real estate investment guide, sections 4.3–4.4.
Can a landlord's business qualify for Small Business Relief?
This is a separate election for eligible resident taxpayers. Check whether revenue exceeded AED 3 million in the relevant or any earlier tax period. The Ministry of Finance extended the relief to eligible tax periods ending on or before 31 December 2029. The FTA still requires eligible taxpayers to register, submit a simplified return and keep their records. Ministry of Finance extension, Ministerial Decision No. 73 of 2023, Article 2 and FTA filing notice.
What deadlines apply to an individual landlord's business?
FTA Decision No. 3 sets 31 March of the following year as the registration deadline for a resident individual who crosses the turnover threshold. The law generally gives nine months after the tax period ends to file the return and pay any tax due. For a resident individual's calendar year ending 31 December 2026, that means registration by 31 March 2027 and ordinary filing and payment by 30 September 2027, assuming the rules above apply. FTA Decision No. 3 of 2024, Article 5 and UAE Corporate Tax Law, Articles 48 and 53.
The FTA gives a different registration rule for non-resident individuals. Its clarification addresses a UAE permanent establishment whose turnover crosses AED 1 million in the calendar year. The deadline is three months from meeting the requirements to be subject to tax. If you live abroad, ask the FTA which status and deadline apply to your letting arrangement. Section 3 of its guide explains how a tax treaty can affect residence. FTA real estate investment guide, FTA Corporate Tax registration clarification and FTA Decision No. 3 of 2024, Article 5.
What should you keep if you buy off-plan to let?
Put the buyer's name from the purchase agreement next to the proposed landlord's name and capacity in the lease or operator contract. Check who will earn the rent once the unit is ready. If the forecast assumes furnished guest stays, ask who can obtain the permit and on what documents. The off-plan purchase agreement checklist sets out where to look in the sale contract itself. FTA real estate investment guide, sections 4.2 and 5 and DET Holiday Homes permit service.
Keep leases, permits, operator contracts and statements that show gross receipts and costs. The Corporate Tax Law generally requires a taxable person to retain supporting records for seven years after the end of the relevant tax period. If an apartment moves from an annual lease to a licensed holiday home, keep the old lease, the start date of the new arrangement and receipts for each period. If one bill covers both activities, keep how you worked out each share. UAE Corporate Tax Law, Article 56 and FTA real estate investment guide, section 4.4.
To compare the money you keep under each arrangement before tax, work out the paid nights a holiday let needs to match an annual lease.
If you live abroad, use the bank account checklist for collecting Dubai rent to check which payments your bank can receive and how you’ll reconcile them against the lease.
What else do Dubai landlords ask about Corporate Tax?
What if you own the flat jointly?
The FTA asks each owner to look at their share of income and their own circumstances. Its co-ownership example includes licensed holiday homes and separate ordinary leases, with different treatment for the two streams. Bring the title, the permit and the agreement that shows each owner's share when you ask about your arrangement. FTA real estate investment guide, section 4.5.
What if a company holds the property?
The individual rule applies to the person's own qualifying property activity. A company is a separate taxpayer under the ordinary Corporate Tax rules. If one person owns both the property and the company, the FTA distinguishes a company earning rent on its own account from one collecting it for the owner. The rights in the agreements matter. UAE Corporate Tax Law, Articles 11–12 and FTA real estate investment guide, example 12.
Still choosing who’ll own the property? Compare the DLD paperwork for a company purchase and a personal purchase before you reserve.
If a foreign company earns rent from UAE property, Cabinet Decision No. 35 of 2025 treats that income as a connection to the UAE for Corporate Tax registration. Show the FTA the purchase and letting agreements if the property is held through a foreign entity and you need to confirm who registers. Cabinet Decision No. 35 of 2025, Articles 2 and 4.
Does the exclusion cover the sale of a rental property?
The FTA's definition covers selling, letting and subletting. The licensing test still applies to the particular activity. If you plan to sell after running the home through a licensed business, show the FTA how you bought, held and let it, and ask how the sale is treated. FTA real estate investment guide, sections 4.2–4.3.
Does this answer what you owe outside the UAE?
This is the published UAE Corporate Tax rule. If you report income in another country, ask that country's tax authority how it treats the rent and what documents it accepts. If the charge you're looking at is on a Dubai utility bill, see the Dubai Municipality housing fee guide.
Who can clarify the tax treatment before you sign?
Ask DET about a required holiday-home permit and the FTA about how the tax rules apply to the activity. Keep the signed or proposed contract, title, permit details and an example of how payment flows. The Ministry's FAQs direct registration and filing questions to the FTA, which offers Private Tax Clarifications for specific Corporate Tax questions. Ministry of Finance FAQs and DET Holiday Homes permit service.
Sources
- Federal Tax Authority — Real Estate Investment for Natural Persons (CTGREI1) — tax.gov.ae · checked
Sections 4 and 5 cover leases, licensing, agents, co-ownership, excluded costs, separate records and the AED 1 million calendar-year test.
- UAE Legislation — Cabinet Resolution No. 49 of 2023 — uaelegislation.gov.ae · checked
Articles 1–3 define real estate investment and the gross turnover threshold of AED 1 million per calendar year.
- UAE Ministry of Finance — Treatment of natural persons undertaking a business — mof.gov.ae · checked
Explains the calendar-year threshold and distinguishes ordinary rental income from business turnover in its example.
- UAE Ministry of Finance — Corporate Tax in the UAE — mof.gov.ae · checked
Explains the starting point for taxable income and the nine-month deadlines.
- UAE Ministry of Finance — Corporate Tax FAQs — mof.gov.ae · checked
Directs registration, return and implementation questions to the FTA.
- UAE Ministry of Finance — Federal Decree-Law No. 47 of 2022 and amendments — mof.gov.ae · checked
Rules on taxable persons, rates, taxable income, payment and return deadlines in months, and records in years.
- UAE Legislation — Cabinet Resolution No. 116 of 2022 — uaelegislation.gov.ae · checked
AED 375,000 taxable income boundary between the ordinary 0% and 9% bands.
- UAE Ministry of Finance — Cabinet Decision No. 35 of 2025 — mof.gov.ae · checked
Articles 2 and 4 set out the UAE property income connection and registration rule for foreign legal entities. Applies to tax periods starting from 1 January 2025.
- Federal Tax Authority — Decision No. 3 of 2024 — tax.gov.ae · checked
Article 5 sets 31 March and three-month registration deadlines for qualifying resident and non-resident individuals, respectively.
- Federal Tax Authority — Corporate Tax registration timelines — tax.gov.ae · checked
Clarifies the non-resident individual permanent-establishment test and AED 1 million turnover threshold.
- UAE Ministry of Finance — Small Business Relief extension — mof.gov.ae · checked
Ministerial Decision No. 131 of 2026 extends the AED 3 million relief through periods ending by 31 December 2029.
- UAE Ministry of Finance — Ministerial Decision No. 73 of 2023 — mof.gov.ae · checked
AED 3 million revenue test for the relevant and prior tax periods. Read the original end date with the 2026 amendment.
- Federal Tax Authority — Corporate Tax filing and payment notice — tax.gov.ae · checked
Nine months from tax period end and continued registration, return and records duties under Small Business Relief.
- Dubai Department of Economy and Tourism — New Holiday Homes permit — dubaidet.gov.ae · checked
Unit registration, approval status and the documents the department requests.
- Federal Tax Authority — Private Tax Clarifications — tax.gov.ae · checked
Where to ask about a specific Corporate Tax or VAT issue.
Next stepDubai Properties Service Charges: DLD Index & Calculator →
More in Ownership costs
Start here: Dubai Properties Service Charges: DLD Index & Calculator
- What Is the Early Mortgage Settlement Fee in Dubai?
- Can a Mortgage Cover Your Final Handover Payment in Dubai?
- Mortgage vs Payment Plan in Dubai (Cash at Handover)
- Dubai property payment plans compared by cash due date
- Is VAT Charged on Property in Dubai? A Buyer’s Guide
- District cooling bill Dubai: charges and query steps