EIBOR in UAE property financing: mortgage checks for 2026
How EIBOR affects a UAE mortgage: benchmark plus margin, reset dates and a worked monthly-payment example to check before accepting finance.
EIBOR matters because a mortgage linked to it can become more or less expensive when the benchmark changes. Check how your contract adds the bank's margin to the benchmark and whether a minimum rate applies. Find the benchmark tenor, margin and next reset date before comparing monthly payments.
What is EIBOR?
EIBOR stands for Emirates Interbank Offered Rate. The Central Bank of the UAE (CBUAE) describes it as the benchmark for lending between banks in UAE dirhams, also used as a reference for mortgages and other loans.
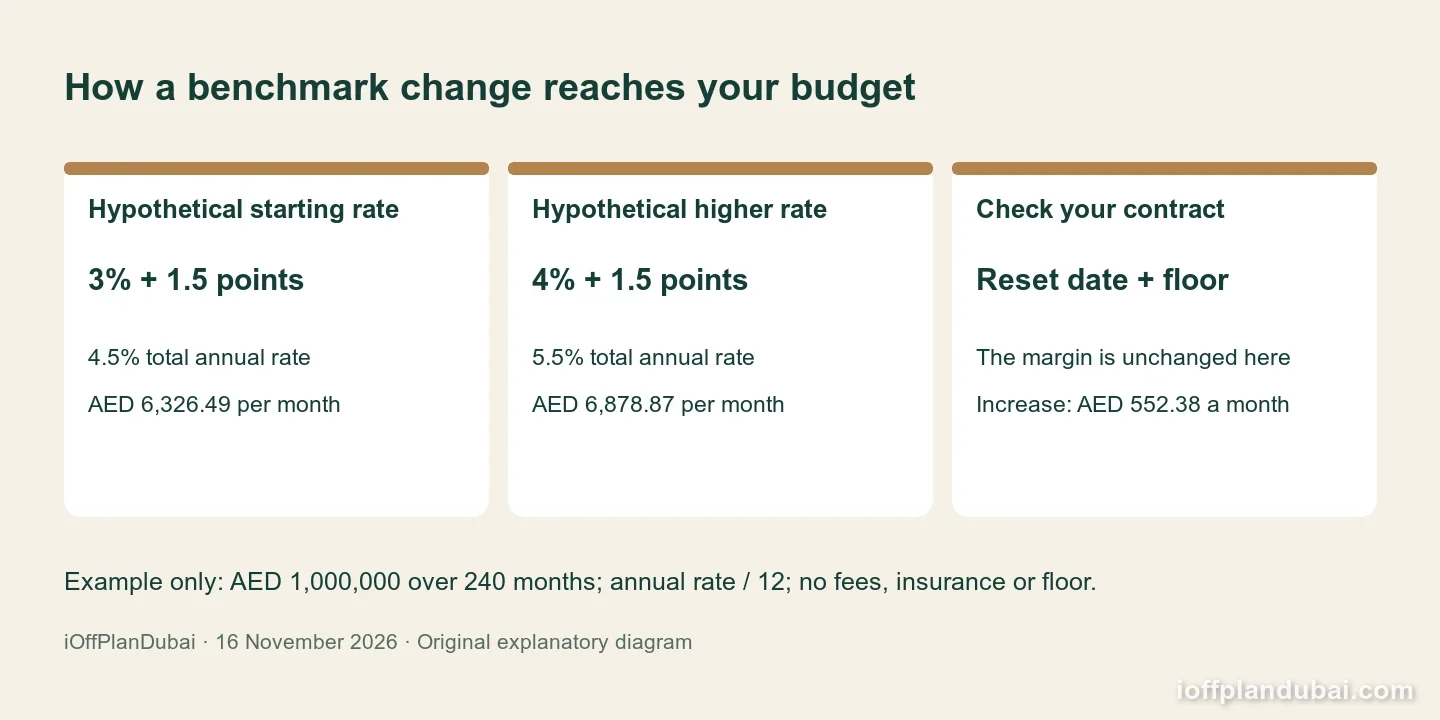
Your bank adds its agreed margin. Hypothetical example: a benchmark of 3% a year, plus a bank margin of 1.5 percentage points, gives a total annual rate of 4.5%. If the benchmark becomes 4% and the margin stays unchanged, the total becomes 5.5%, before any contract floor or other adjustment.
Source · Central Bank of the UAE, EIBOR Rates · Checked 16 November 2026. Example figures are hypothetical, not current fixings or an offer.
When does an EIBOR change reach your mortgage?
Read the reset clause. A three-month benchmark doesn't mean your loan ends in three months, and a published rate change doesn't necessarily alter tomorrow's payment.
HSBC UAE provides a useful product example: its three-month EIBOR variable mortgage is reviewed quarterly, with a margin fixed for the loan's life. Its fixed-rate product offers an initial one, two, three or five years, followed by a three-month EIBOR variable period. Check your own lender's terms separately.
| Find this in the offer | Ask the bank |
|---|---|
| Benchmark tenor | “Which EIBOR series does this loan use?” |
| Fixing rule | “Which published date supplies my rate?” |
| Reset schedule | “When does my next rate take effect?” |
| Fixed-period expiry | “What formula applies afterwards?” |
| Minimum rate | “Is there a floor, and how is it applied?” |
Source · HSBC UAE, Mortgage rates, undated product page · Checked 16 November 2026. This is a product-structure example, not a recommendation or personal quote.
How much could one percentage point add to your payment?
Hypothetical example: borrow AED 1,000,000 over 20 years, or 240 months, with equal monthly repayments. Assume the annual rate is divided by 12, no fees or insurance, and no rate floor.
| Hypothetical total annual rate | Monthly payment | Difference |
|---|---|---|
| 4.5% | AED 6,326.49 | Starting scenario |
| 5.5% | AED 6,878.87 | AED 552.38 more per month |
The calculation is M = P × r × (1 + r)^n ÷ [(1 + r)^n − 1]. P is the balance, r is the annual rate divided by 12, and n is the number of months. For the first row, P = 1,000,000, r = 0.045 ÷ 12 and n = 240. Payments are rounded to two decimal places.
Ask the bank to run both scenarios using your remaining balance and term. Its day-count method, reset timing and charges can change the result. The mortgage versus payment-plan guide helps you put those repayments beside the developer's deadlines.
Where can you check the benchmark?
Open the CBUAE EIBOR page and match the published date and tenor to your contract. Save the relevant entry and ask the bank to show which fixing it used.
No current EIBOR figure is quoted here. The check date, 16 November 2026, isn't necessarily your loan's fixing or reset date.
Source · Central Bank of the UAE, EIBOR Rates and history · Checked 16 November 2026.
What must the bank explain before you sign?
Request the Key Facts Statement (KFS) and written offer. CBUAE's Consumer Protection Standards, sections 2.1.1.35–36, require disclosure of rate type, calculation, separate benchmark and margin, and revision frequency. Sections 2.1.1.37–38 cover fees and whether they recur.
Ask the bank to mark the post-fixed-period formula, then calculate the payment using your balance. Ask for arrangement costs, valuation, insurance and early-settlement terms alongside the rate. Keep unquoted amounts blank until the bank supplies them.
Watch out: a small margin alone doesn't establish the cheapest total loan. A floor or additional charge can change the comparison.
Source · Central Bank of the UAE, Consumer Protection Standards, sections 2.1.1.19 and 2.1.1.35–38 · Checked 16 November 2026.
How should you budget for an off-plan purchase?
Give the lender the developer's payment schedule and ask which amounts it can finance, under what conditions and by which dates. Compare the answer with the balance due under your sale and purchase agreement.
List each developer instalment with its amount in AED and due date. Keep annual service charges in a separate budget line. Ask the bank to confirm the amount and release conditions before relying on a mortgage for handover.
When comparing bank finance with developer instalments, use the project escrow and payment-schedule checks to keep the instalment trigger separate from construction-money releases.
What else do borrowers ask?
Will payments fall as soon as EIBOR falls?
Check the fixing date, reset date and any floor. Ask the bank for the next repayment amount in writing rather than applying today's benchmark to the current instalment yourself.
Does a fixed mortgage make EIBOR irrelevant?
Read what happens when the fixed period ends. If the loan then follows EIBOR plus a margin, ask for the formula and a payment illustration before accepting the initial offer.
Does EIBOR predict property prices or rental returns?
The primary sources cited here don't give such a forecast. EIBOR helps you examine borrowing costs. Check the price, rent and ownership costs of the specific property separately, starting with the Dubai buying checklist.
Put the next reset date in your calendar and ask the bank to calculate the payment you would owe if the benchmark rose by one percentage point.
Buying while living abroad? Check non-resident mortgage eligibility and the cash needed before relying on a quoted rate.
Sources
- Central Bank of the UAE — EIBOR Rates — centralbank.ae · checked
Defines Emirates Interbank Offered Rate as the AED interbank lending benchmark also used for mortgages. Provides dated fixings and historical data. No current fixing quoted in this article; percentages in the worked example are hypothetical annual rates.
- HSBC UAE — Mortgage rates — hsbc.ae · checked
Undated product page describes three-month EIBOR variable loans with quarterly review and a margin fixed for the loan life. Fixed periods of one, two, three or five years then move to three-month EIBOR plus margin. Structure example only, not a personal quote.
- Central Bank of the UAE — Consumer Protection Standards — centralbank.ae · checked
Sections 2.1.1.19 and 2.1.1.35–38 cover Key Facts Statements, rate type and calculation, benchmark plus margin, revision frequency, and fees. No individual rate, fee or approval established.
Next stepDubai properties service charges (2026 Fees Checklist) →
More in Ownership costs
Start here: Dubai properties service charges (2026 Fees Checklist)
- Service charges in Dubai: bill checks (2026 Update)
- Owners association Dubai: fees and roles (Checklist)
- Mortgages in Dubai for non-residents (2026 Checklist)
- Mollak service charges: payment checks (2026 Update)
- Cheapest property in Dubai: areas and buying costs (2026)
- Mortgage vs payment plan in Dubai: compare the cash due