Who Qualifies for Dubai’s First Time Home Buyer Scheme?
Check age, residency and ownership requirements, the AED 5 million cutoff and how mortgage limits affect your upfront cash.
As of 18 November 2026, you qualify for Dubai’s first time home buyer scheme if you live in the UAE, are 18 or over, don’t currently own a freehold residential property in Dubai and are buying a home priced below AED 5 million. The Central Bank caps mortgages on off-plan purchases at 50% of property value, including for buyers eligible for the programme. DLD, programme eligibility · Central Bank of the UAE, mortgage rules, Article 3 · Checked 18 November 2026.
Who qualifies for the first time home buyer scheme in Dubai?
Check both buyers' eligibility before you put both names on the booking. Dubai Land Department (DLD) and the Department of Economy and Tourism launched the programme in July 2025.
| Question | What DLD publishes |
|---|---|
| Can expats apply? | Yes. UAE residents of any nationality can apply from age 18. |
| What if you own another home? | The eligibility criteria refer to current freehold residential ownership in Dubai. The FAQ allows property in another emirate or a non-freehold location, subject to its Dubai ownership condition. |
| Is AED 5 million eligible? | DLD's current application page says below AED 5 million. Ask DLD if your unit is right at the cutoff or an offer changes the contract value. |
| Can you buy jointly? | DLD says both joint buyers must be eligible. Ask your bank separately whether it accepts your proposed co-borrowing arrangement. |
| Can you pay cash? | Yes. DLD says a mortgage is optional. |
If you own a share in a family home, have a provisional registration on another Dubai property or previously sold a home outside the programme, give DLD your exact ownership history and ask how it applies the criteria. The public FAQ uses both “freehold residential property” and the broader “freehold property” in different answers. Send DLD the full title details if that difference matters to your application. For citizen grants and housing support, see the UAE government home buyer schemes guide. DLD, eligibility and FAQ · Dubai DET, launch announcement · Checked 18 November 2026.
How much will a bank lend on a ready or off-plan home?
Loan-to-value, or LTV, is the loan as a share of the property value the lender accepts. The Central Bank of the UAE sets the maximum. Ask the bank which row it will use and what value it will lend against. A lender can offer less after valuing the property and checking your finances.
| Mortgage category | UAE nationals | Expatriates |
|---|---|---|
| Ready first home you’ll live in, valued at AED 5 million or less | Up to 85% | Up to 80% |
| Ready first home you’ll live in, valued above AED 5 million | Up to 75% | Up to 70% |
| Subsequent home or investment property, other than off-plan | Up to 65% | Up to 60% |
| Off-plan purchase, any value or borrower category | Up to 50% | Up to 50% |
At exactly AED 5 million, DLD's programme page says below that price, while the Central Bank’s financial stability report includes AED 5 million in the higher first-home lending bracket. Have the bank confirm the value it accepts and the lending bracket it uses if your purchase is at that boundary. The owner-occupier category applies to one property per borrower. If you plan to let the home out, tell the bank before it quotes. Central Bank of the UAE, mortgage rules, Article 3 · Central Bank of the UAE, Financial Stability Report 2025, pages 36–37, table 4 · DLD, programme eligibility · Checked 18 November 2026.
What cash would you need on an AED 2 million home?
Hypothetical example. You’re an expatriate buying a first home to live in at AED 2 million. Assume the lender accepts that value and offers the maximum for the category. For a ready home, 80% × AED 2,000,000 gives a loan of AED 1,600,000 and leaves AED 400,000 of the price for you to fund. For a purchase financed off-plan, 50% × AED 2,000,000 gives AED 1,000,000 and leaves AED 1,000,000 of the price to fund, spread according to the contract and financing dates.
If the ready home's lender accepts a value of AED 1,850,000, 80% of that is AED 1,480,000. You would need AED 520,000 toward the price, AED 120,000 more than you budgeted using the sale price alone. Add the fees to each cash figure. On a sale at AED 2 million, the full 4% adds AED 80,000 if the agreement assigns it to you. Ask for the applicable fixed charges as well. Use the Dubai off-plan registration fee guide for a first sale from a developer. Central Bank of the UAE, mortgage rules, Articles 2–3 · DLD, property sale fees · Checked 18 November 2026.
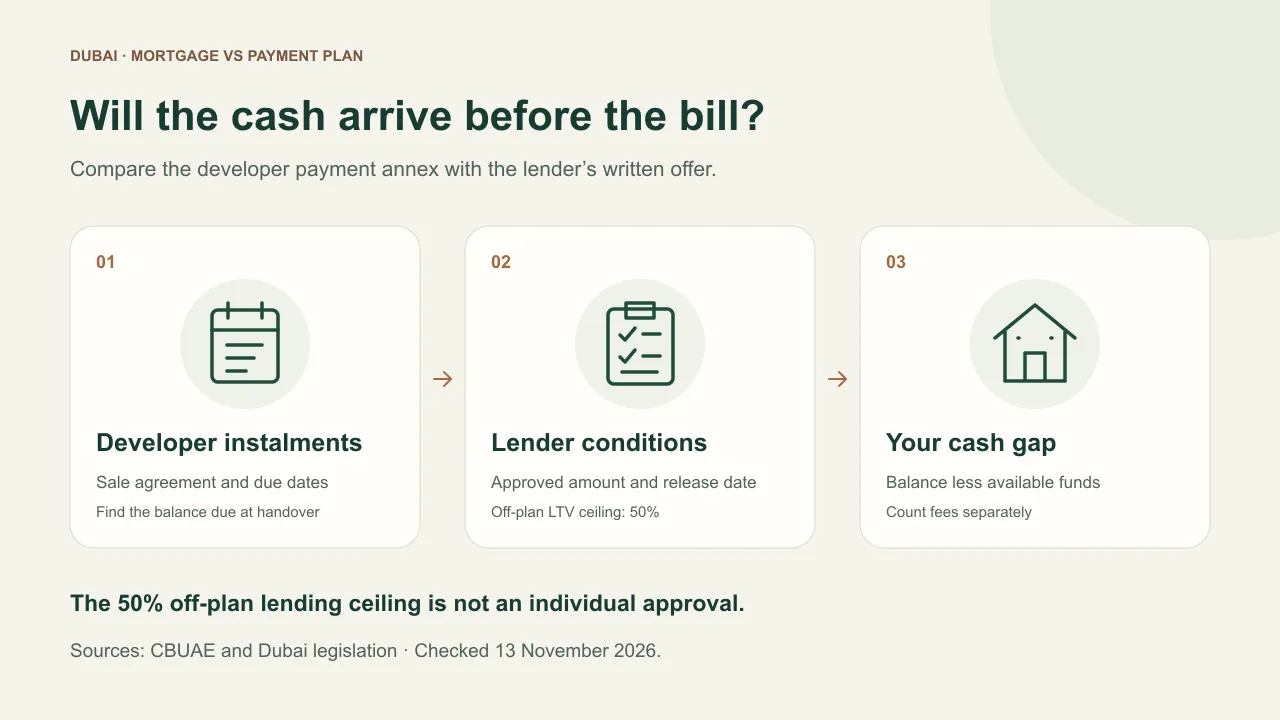
For a home under construction, get the dates before you reserve. List each instalment and write the amount the bank confirms it can release by that date beside it. The gap is the cash you need to have ready for that instalment. If you're counting on borrowing at handover, ask the bank what valuation, completion documents and credit checks it will need then. Use the mortgage and developer payment plan comparison to lay out both schedules. Central Bank of the UAE, mortgage rules, Articles 2 and 4 · Checked 18 November 2026.
If the bank comes back with a lower figure, use the valuation cash-gap calculation to see how much you'd still owe at transfer.
What can lower your loan even if you qualify for the programme?
The bank checks what you can repay as well as the property's value. The Central Bank’s standard debt-burden cap is 50% of gross monthly income, including the proposed mortgage and your other repayments. The rules cap loan size at up to eight times annual income for UAE nationals and seven times for expatriates, and the mortgage term at 25 years. The lender sets its own maximum age at final repayment. Ask for the monthly payment it uses in the approval calculation and which existing debts it counts.
Hypothetical debt check for an expatriate. At AED 30,000 gross monthly income, a 50% debt-burden cap gives AED 15,000 for monthly repayments. If the bank counts AED 4,000 of existing commitments each month, that leaves AED 11,000 before its other affordability checks. The rules call for a stress test at 2 to 4 percentage points above the applicable rate. If you have a starting rate that expires, ask what the rate is linked to afterwards and what that does to your payment. See the EIBOR and mortgage reset guide if your quote uses the Emirates Interbank Offered Rate. Central Bank of the UAE, mortgage rules, Article 3 · Central Bank of the UAE, Financial Stability Report 2025, pages 36–37 · Checked 18 November 2026.
Set aside your own funds for the down payment, as the mortgage rules require. DLD's offer of instalments on eligible cards concerns registration fees. Ask the bank how a new card instalment would affect the commitments it counts before you take it on. Central Bank of the UAE, mortgage rules, Article 2 · DLD, programme benefits · Checked 18 November 2026.
If you’re buying off-plan, keep the signed unit plan with your purchase agreement. The Dubai handover guide to unit area differences shows which figures to compare if the final plan changes.
How do you apply and compare the offers?
- Register on the DLD website or in Dubai REST. Submit the information the service asks for. If DLD confirms you qualify, it emails a QR code. DLD says the code stays valid until you purchase and register a property. There’s no programme application or participation fee.
- Ask for the offer on the exact unit. For an off-plan purchase, ask the participating developer about reserved stock, the price, payment dates and offer expiry. For a ready home, show the code to a participating bank and ask what the bank offers on that property. DLD lets you approach several partners, with benefits limited to one developer and one bank.
- Get the figures in writing. Ask for the full amount you need to pay before the bank releases money, the deposit conditions, the loan amount and fees. Ask for the valuation and insurance costs and the rate or profit after any introductory period. If you’re self-employed or your pay varies, ask which income records the bank accepts and which earnings it will count. Ask for the date when the lender's offer expires.
DLD lists priority access to selected launches and flexible payment plans among the off-plan benefits. To compare a programme price with the developer’s ordinary offer, ask for the same unit on both quotes with the instalment dates and fees shown. Emirates NBD, for example, describes a ready-home route and advertises no application fee for its programme offer. Ask what you'd still pay for valuation or other services. DLD’s partner list includes Commercial Bank of Dubai, Dubai Islamic Bank, Emirates NBD, Emirates Islamic and Mashreq. There's no single discount, processing deadline or mortgage rate we could confirm across all partners. DLD, application and partner FAQ · Emirates NBD, programme offer · Checked 18 November 2026.
What if the approval or offer doesn't come through?
If you’ve already signed for an off-plan home and a bank delay puts an instalment in doubt, check the missed off-plan payment procedure before asking the developer to change your schedule.
- DLD says you're ineligible. Read the reason first. DLD says you may reapply if your circumstances change and you meet its criteria. For a mismatch in the property record or an unclear response, call 800 4488 with the application details.
- The bank approves less than you need. Ask whether it used a lower valuation, a smaller lending percentage or a lower amount based on affordability. That tells you which number to use before you agree a price.
- The developer wants a booking payment before the bank decides. Ask which sums you can recover if the bank declines, the valuation is low or the bank won't release funds on time. Get the answer on the signed terms for that unit.
If you live abroad, DLD requires UAE residency for this programme. You can still look into the separate Dubai mortgage route for non-residents and ask a lender to confirm its criteria. DLD, programme FAQ and support · Central Bank of the UAE, mortgage rules, Articles 2–4 · Checked 18 November 2026.
What else do first-time buyers ask?
Can you use the programme again after selling?
If you bought through the programme and later sell, DLD says you can't use it again. When your situation involves an earlier purchase outside the programme, send DLD the ownership history and ask the bank separately which lending category applies. DLD, repeat participation FAQ · Checked 18 November 2026.
Does the programme waive the DLD fee?
DLD says regular registration fees and developer or bank charges apply unless a special offer says otherwise. Eligible card instalments change when you pay. Ask the partner for the full amount in AED, who pays each charge and the first due date. DLD, programme fees and benefits · Checked 18 November 2026.
Does a QR code give you an 80% or 85% loan?
No. The QR code shows the bank you’re eligible for the programme. The loan is still the bank’s decision, and the Central Bank percentages are ceilings. Give the bank your QR code, the unit details and the developer's instalment schedule. Ask for a written offer with the approved amount, any conditions still open and the earliest date the bank can release funds. Line that up with the first payment you’re relying on it to cover. DLD, QR code FAQ · Central Bank of the UAE, mortgage rules, Articles 2–4 · Checked 18 November 2026.
Sources
- Dubai Land Department — First Time Home Buyer Overview — dubailand.gov.ae · checked
UAE residence, age 18 and above in years, qualifying value below AED 5 million, ownership, joint applications, QR code and partner benefits.
- Dubai Department of Economy and Tourism — Programme launch — dubaidet.gov.ae · checked
Launch announced on 2 July 2025 by DET and DLD.
- Central Bank of the UAE — Regulations Regarding Mortgage Loans, Circular 31/2013 — rulebook.centralbank.ae · checked
Consolidated PDF of 8 April 2020, Articles 2–4. Covers appraisal, own funds, lending limits in percent, debt burden, maximum term in years and loan disclosures.
- Central Bank of the UAE — Financial Stability Report 2025 — centralbank.ae · checked
Pages 36–37, table 4 confirms the AED 5 million inclusive threshold for both owner-occupier categories and mortgage limits as percentages of property value.
- Emirates NBD — First-Time Home Buyers Program — emiratesnbd.com · checked
Bank-specific example of a ready-home route and a published application-fee offer. Individual terms depend on bank policy and lending limits.
- Dubai Land Department — Property Sale Registration — dubailand.gov.ae · checked
Standard sale registration shares in percent and service partner charges in AED plus VAT.
Next stepDue diligence →
More in Due diligence
Start here: Due diligence
- Who Pays the 4% DLD Fee on a Dubai Off-Plan Purchase?
- Golf Simulator in Dubai Homes (Resident Checklist)
- Tennis Courts in Dubai Communities (Buyer Checklist)
- Freehold Areas in Dubai: 10 Places to Buy (2026 Update)
- Getting an Escrow Account in Dubai (2026 Checklist)
- Who Gets the Manager's Cheque for a Dubai Property Transfer?