Mortgages in Dubai for non-residents (2026 Checklist)
Can non-residents get a Dubai mortgage? Check lender eligibility, cash needed, documents, valuation and registration before committing to a purchase.
Mortgages in Dubai for non-residents depend on the lender’s eligibility and approval conditions.
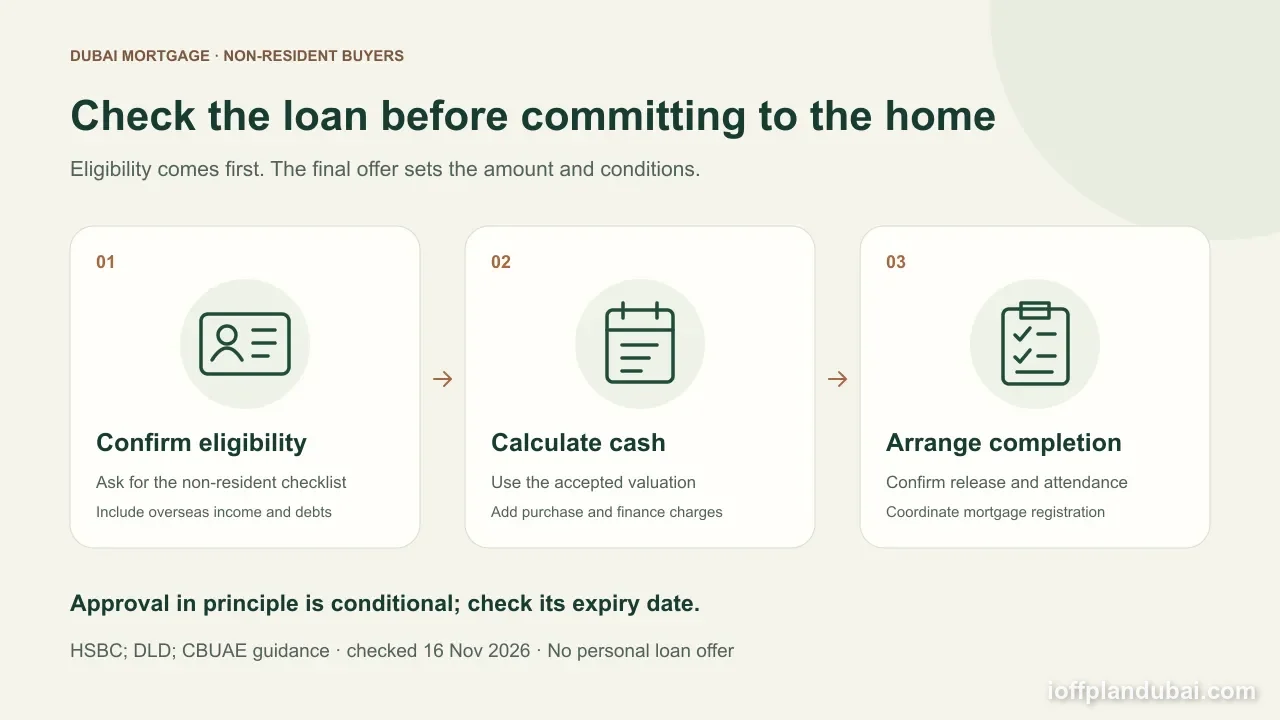
You can get a Dubai mortgage while living outside the UAE, if a lender accepts your circumstances and the property. HSBC, for example, advertises non-resident lending up to 60% of property value for eligible customers. Check eligibility and your cash budget before signing for a home.
How do mortgages in Dubai for non-residents work?
Start with the lender's non-resident team. HSBC requires Private Bank or Premier eligibility. That product is one documented route, not a market-wide lending limit or a recommendation.
Ask the bank to confirm whether it accepts your country of residence, income currency, employment and chosen building. Request its minimum income, maximum term and age limits in writing. A resident-expatriate product page doesn't answer those questions for someone living abroad.
Source · HSBC UAE, non-resident mortgages, undated · Checked 16 November 2026.
How much cash will you need?
At 60% loan-to-value, the loan covers 60% of the accepted property value. That's HSBC's advertised maximum for this product; your approval may be lower.
Hypothetical example: assume a purchase price and accepted valuation of AED 2,000,000, with 60% finance. The loan is AED 2,000,000 × 60% = AED 1,200,000. You need AED 800,000, plus purchase and finance costs.
Now assume the valuation is AED 1,800,000 and the lender applies 60% to it. Finance becomes AED 1,080,000, leaving AED 920,000 towards the same purchase price. Ask which value the bank uses before treating your deposit budget as settled.
Keep the purchase checklist beside that calculation.
Source · HSBC's advertised financing limit · Checked 16 November 2026. Both calculations use hypothetical assumptions.
Which documents should you prepare?
Ask for a checklist headed non-resident, tailored to your employment and country. HSBC's general application page lists income evidence, debts, property documents and proof of down-payment funds, but also includes UAE resident documents.
| Prepare for the lender's review | Ask before commissioning documents |
|---|---|
| Passport and overseas address evidence | Which documents and validity periods does the bank accept? |
| Salary or business-income records | Which statement periods, currencies and translations are required? |
| Existing debt details | Which overseas loans and credit commitments must be included? |
| Down-payment evidence | What proof of funds and transfer history does the bank require? |
| Property papers | Is this building and unit eligible for the loan? |
Send personal financial documents through the bank's confirmed secure channel. Don't put passport scans or account statements into a public property enquiry.
Source · HSBC UAE, application requirements, undated · Checked 16 November 2026. The questions above help obtain your specific checklist.
What should you compare in the offer?
Request the Key Facts Statement and written loan terms. Central Bank disclosure standards cover the rate, charges and repayment information. For a variable loan, identify the benchmark, margin and reset frequency; the EIBOR guide explains how those reach your payment.
| Cost or condition | Get a written answer |
|---|---|
| Interest or profit | Initial rate, fixed period, later rate and any minimum rate |
| Bank charges | Arrangement, valuation, insurance and early-settlement costs |
| Cash release | Conditions still outstanding and expected release date |
| Currency conversion | Cost of converting your income into AED and transferring repayments |
Ask the bank to show the monthly payment at a higher rate. Put the building's annual service charges outside the mortgage figure so you can see the full housing cost.
Source · Central Bank of the UAE, Consumer Protection Standards, Article 2 · Checked 16 November 2026. Currency budgeting is a suggested comparison check.
How is the mortgage registered?
Coordinate registration with the lender and registration trustee. DLD's individual checklist includes a bank letter, three bank-certified mortgage contracts signed by both parties, and a passport copy for non-resident foreigners. A representative needs a legal power of attorney; provisional-sale properties have an e-NOC requirement.
DLD lists a mortgage registration charge of 0.25% of mortgage value, with additional applicable charges. Hypothetical example: AED 1,200,000 × 0.25% = AED 3,000 for that component alone. Request a transaction-specific breakdown, including trustee and document charges.
HSBC's non-resident page lists a AED 2,625 valuation fee including VAT and an in-person loan-document signature. Confirm the attendance arrangements before booking travel.
Sources · Dubai Land Department, mortgage registration · HSBC UAE, non-resident mortgages · Checked 16 November 2026.
What can go wrong before completion?
Watch out: an Approval in Principle isn't guaranteed finance. HSBC says its approval in principle lasts 60 days. Keep its expiry beside the sale agreement's deadlines.
If the valuation is low, recalculate the cash gap before proceeding. If approval expires, ask the bank what must be refreshed. Have your adviser review what the sale contract says about a declined loan, missed deadline and deposit refund before signing.
Source · HSBC UAE, approval in principle · Checked 16 November 2026. Recovery steps are preparation advice.
For a developer instalment, check the recipient separately using the Dubai real estate escrow requirements; a mortgage offer doesn't identify your project's payment account.
Dubai's resident first-time buyer route has a residency condition. Use the UAE housing schemes and first-time buyer checks to distinguish that programme from citizen housing assistance before assuming a benefit applies to a non-resident loan.
FAQ
Can a mortgage cover an off-plan instalment?
Don't assume it will. Ask the lender whether it finances that project at that stage and when it can release funds. Use the mortgage versus developer payment-plan guide to put the bank's conditions beside each instalment.
Is the advertised rate my rate?
You need a dated personal offer to know. Ask for the annual rate, all charges and the repayment schedule. Compare the rate after any fixed period as well as the opening payment.
Can I complete the whole loan from abroad?
Confirm this with the lender before agreeing a completion date. HSBC's non-resident page calls for an in-person loan-document signature. DLD's representative-document option doesn't establish that a lender will waive its own attendance requirement.
Ask the lender to confirm your eligibility and property before you pay a non-refundable purchase deposit.
Sources
- HSBC UAE — Non-resident mortgages — hsbc.ae · checked
Advertises up to 60 percent loan-to-value for eligible Private Bank or Premier customers, valuation fee AED 2625 including VAT and an in-person loan-document signature. Individual eligibility and terms require confirmation.
- HSBC UAE — How to apply — hsbc.ae · checked
Approval in Principle is conditional and valid for 60 days. General document list includes resident documents; non-residents must obtain a tailored list.
- Dubai Land Department — Mortgage registration application — dubailand.gov.ae · checked
Lists bank letter, certified signed contracts and passport copy for non-resident foreigners through trustees; representative and provisional-sale requirements vary. Mortgage fee 0.25 percent plus other applicable charges.
- Central Bank of the UAE — Consumer Protection Standards — centralbank.ae · checked
Article 2 covers Key Facts Statements, rate disclosures and written credit terms. No personal rate or approval established.
Next stepDubai properties service charges (2026 Fees Checklist) →
More in Ownership costs
Start here: Dubai properties service charges (2026 Fees Checklist)
- Central garden in Dubai homes: access and cost checks
- Service charges in Dubai: bill checks (2026 Update)
- Owners association Dubai: fees and roles (Checklist)
- EIBOR in UAE property financing: mortgage checks for 2026
- Mollak service charges: payment checks (2026 Update)
- Cheapest property in Dubai: areas and buying costs (2026)